A State Registered-Agent Change Does Not Update IRS Address Records
· 7 min read
The practical answer
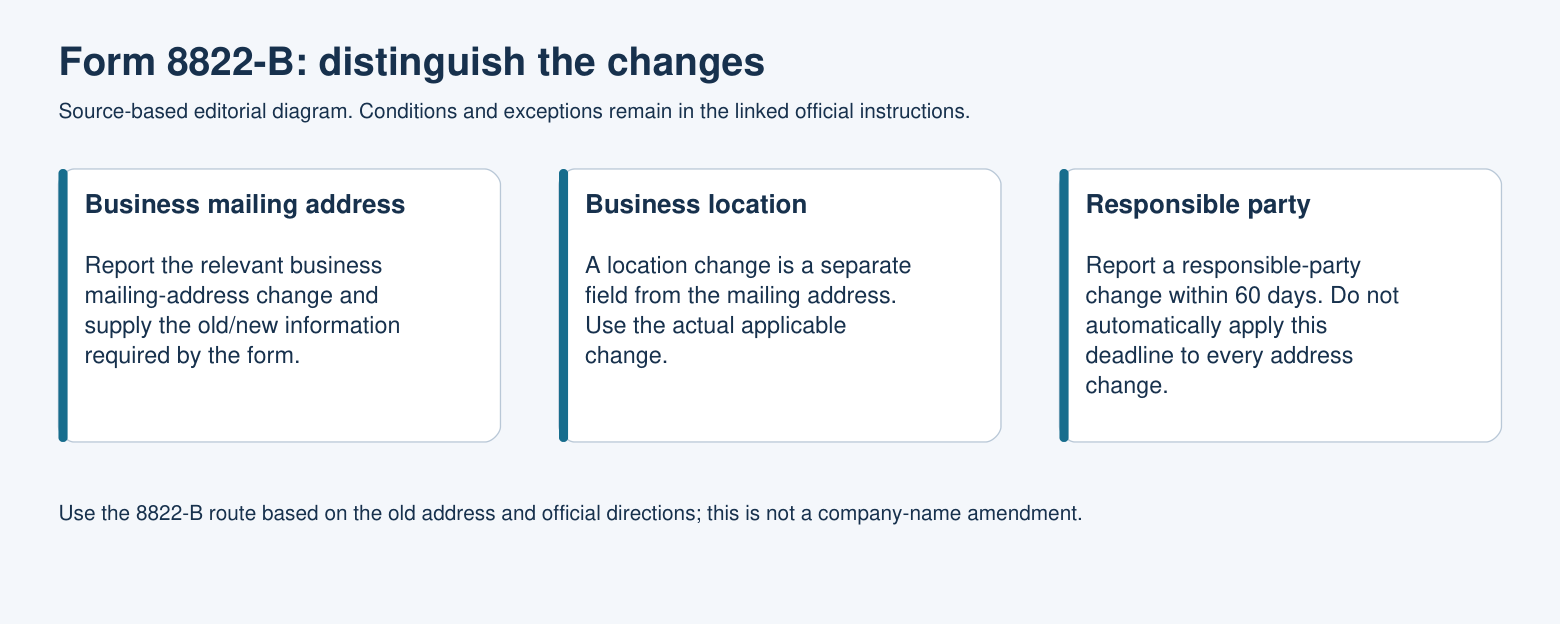
A state business record and an IRS record serve different administrative purposes. When a registered agent changes, collect the before-and-after documents and identify which information belongs to each agency instead of assuming that completing one record automatically answers the other agency's questions. Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address.[1, p.1] [1, p.2] [2, p.2]
Scope and the records behind the answer
The discussion follows the entity, form and transaction conditions identified below. The same label on a different form can have a different purpose. Keep the relevant entity and reporting period visible while you compare the requirements, and treat each stated exception as part of the rule rather than an optional footnote.
Official sources checked: 2026-11-09. Annual tax-year forms and continuously revised forms are identified separately in the references.
A side-by-side preparation table
| Item or question | Official rule or instruction | Conditions and limits | Source |
|---|---|---|---|
| New agent distinct person | The Appointment of New Registered Agent and Office form is for replacing one agent person/company with a different agent person/company. | A current agent’s own address/name update uses a different form. | [1, p.1] |
| Agent change address choices | The agent-replacement form separately asks whether the business mailing address should change to the new registered-office address. | Do not treat that choice as an automatic IRS mailing-address update. | [1, p.2] |
| Purpose | Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.2] |
| Responsible party 60days | An entity with an EIN must report a responsible-party change within 60 days using lines 8 and 9 of Form 8822-B. Do not automatically apply that deadline to every address change. | The entity has an EIN. Its responsible party has changed. | [2, p.2] |
| Route old address | The Form 8822-B mailing destination is selected using the old business address, rather than the new address or the state of formation alone. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.1] |
| Distinct from 8822b | A business-name-only change follows the IRS business-name-change procedure. The stated uses of Form 8822-B are changes to the business mailing address, business location or responsible party; its name field does not make it a general business-name-change application. | Distinguish a business name change from an address or responsible-party change. If several changes occur together, follow each applicable procedure. | [2, p.2] [3] |
Work through the official requirements
New agent distinct person
The Appointment of New Registered Agent and Office form is for replacing one agent person/company with a different agent person/company.[1, p.1]
This applies when: A current agent’s own address/name update uses a different form.
Agent change address choices
The agent-replacement form separately asks whether the business mailing address should change to the new registered-office address.[1, p.2]
This applies when: Do not treat that choice as an automatic IRS mailing-address update.
Purpose
Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address.[2, p.2]
Responsible party 60days
An entity with an EIN must report a responsible-party change within 60 days using lines 8 and 9 of Form 8822-B. Do not automatically apply that deadline to every address change.[2, p.2]
This applies when: The entity has an EIN. Its responsible party has changed.
Route old address
The Form 8822-B mailing destination is selected using the old business address, rather than the new address or the state of formation alone.[2, p.1]
Distinct from 8822b
A business-name-only change follows the IRS business-name-change procedure. The stated uses of Form 8822-B are changes to the business mailing address, business location or responsible party; its name field does not make it a general business-name-change application.[2, p.2] [3]
This applies when: Distinguish a business name change from an address or responsible-party change. If several changes occur together, follow each applicable procedure.
Mailing address
Lines 4a-4b identify the mailing address where the entity receives correspondence. A foreign address must include the city, province or state, postal code and full country name.[4, p.3]
Field/section Where To File: Where To File
Use the current Where To File instructions or current IRS routing for the region of the old address. Do not send the form to the comments or forms-simplification address.[2, p.1]
Representative poa
A representative signing Form 8822-B for the taxpayer must attach a copy of the power of attorney. An unauthorized third party cannot make the change.[2, p.2]
An illustrative preparation scenario
In this hypothetical preparation example, an owner changes registered-agent providers and places the state confirmation into the tax folder. The preparer checks whether the IRS mailing address, business location, or responsible-party information also changed, keeping those questions separate from the state agent record. The preparer checks three points: What changed in the state registered-agent record? Did any IRS-address or responsible-party fact also change? Which agency-specific records support each conclusion? The file remains a working comparison until the relevant facts and applicable instructions have been checked together. No agency outcome is assumed.[1, p.1] [1, p.2] [2, p.2]
This is a planning illustration, not a statement that a particular filing has been accepted or that an entity qualifies for a tax result. Use the source-backed distinctions above to decide what information still needs to be established before a form is completed.
A review sequence you can actually use
- What changed in the state registered-agent record?
- Did any IRS-address or responsible-party fact also change?
- Which agency-specific records support each conclusion?
Write down the answer and the record that supports it, rather than marking a question complete because a field contains text. When two records disagree, identify whether the difference concerns the entity, an individual, the reporting period or the type of change. That makes the remaining question specific enough to resolve against the relevant instruction.
Keep the scope of a preparation service separate from the government requirement. A service intake question may gather information for a workflow; it does not create an exception, extend a deadline or determine whether a transaction is reportable. The cited government material remains the basis for those conclusions.
Questions to settle before moving forward
How should I check purpose?
Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. [2, p.2]
How should I check responsible party 60days?
An entity with an EIN must report a responsible-party change within 60 days using lines 8 and 9 of Form 8822-B. Do not automatically apply that deadline to every address change. The entity has an EIN. Its responsible party has changed.[2, p.2]
How should I check route old address?
The Form 8822-B mailing destination is selected using the old business address, rather than the new address or the state of formation alone. [2, p.1]
How should I check distinct from 8822b?
A business-name-only change follows the IRS business-name-change procedure. The stated uses of Form 8822-B are changes to the business mailing address, business location or responsible party; its name field does not make it a general business-name-change application. Distinguish a business name change from an address or responsible-party change. If several changes occur together, follow each applicable procedure.[2, p.2] [3]
Official sources and versions
- Appointment of New RA and Office — Revised June 2021
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- Business name change
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
Get help with the relevant SpeedEIN workflow
SpeedEIN offers preparation and support for the situations described on its service pages. If you would like assistance, review the relevant service scope, supported entities and current availability before ordering. The service does not replace the government’s decision or remove an obligation imposed by the applicable rules.