An IRS Address Update Is Still Pending When Filing Work Starts: Preserve Both Records
· 5 min read
The answer for this situation
When an IRS address update is still unconfirmed as filing work starts, preserve both the existing-record history and the change-request history. A pending-update pack can show what information was requested, which document was prepared or submitted and what later correspondence actually displays. Do not make the folder look consistent by replacing every older address with the requested one. Entering a new address on Form 7004 does not update IRS address records, and the business update is filed separately rather than attached to a return. The practical goal is to give the filing preparer a clear account of known facts and a specific unresolved address question, not a promise that processing is complete or that any later draft automatically changes the underlying record.[1, p.2] [2, p.2] [1, p.1]
Which facts change the answer?
The selected sources distinguish the business update's purpose, old and new address roles and its mailing-route basis. They also preserve the separate identity-matching issue for Form 7004. This article does not decide which address to use on every later return without its applicable instructions, prescribe repeat update requests or guarantee when IRS processing occurs. Nor does it infer that an unexplained later letter proves the entire update succeeded or failed. Each piece of evidence should be read for the event and record it actually concerns.[1, p.2] [2, p.2] [1, p.1]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
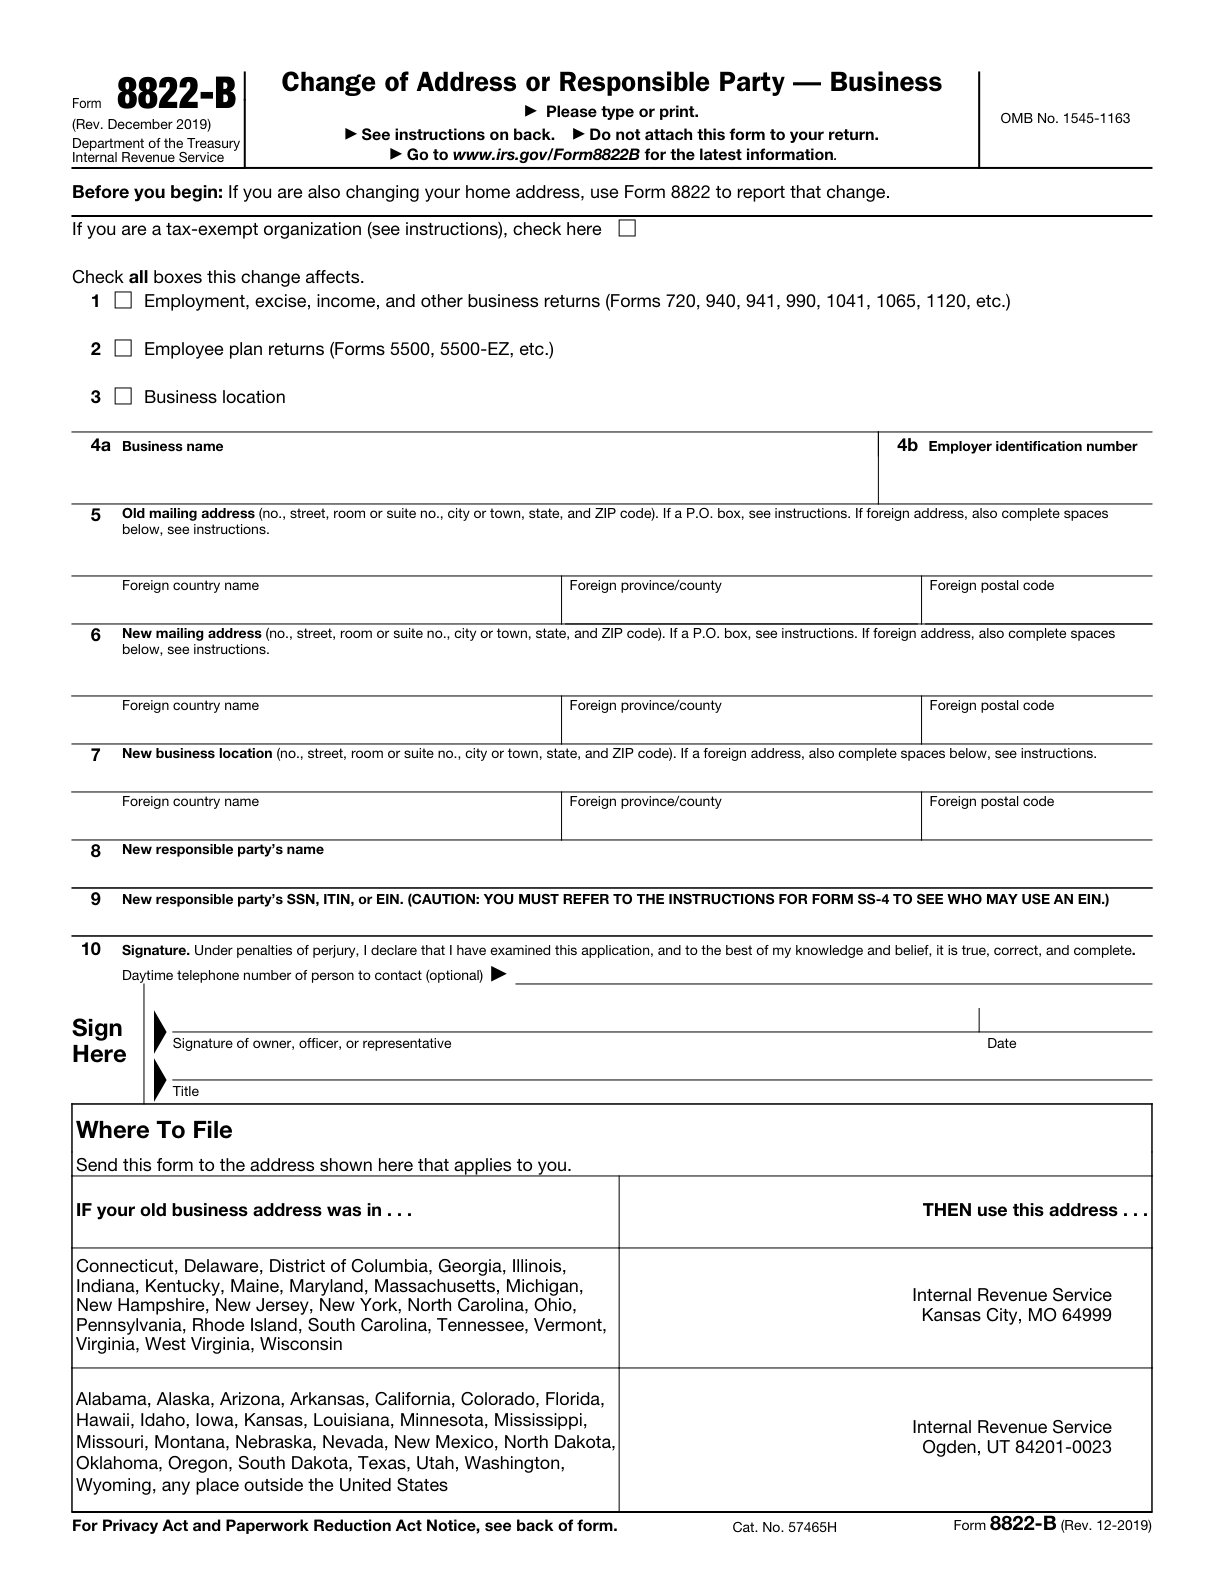
| Purpose | Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. | — | [1, p.2] |
| Address not update | Entering a new address on Form 7004 does not update IRS address records. An address change requires a separate Form 8822 or 8822-B, as applicable. | — | [2, p.2] |
| Route old address | The Form 8822-B mailing destination is selected using the old business address, rather than the new address or the state of formation alone. | — | [1, p.1] |
| Official field 8822-B 5: Old mailing address | Enter the old mailing address, including complete foreign-address fields. The old address determines the filing route. | — | [1, p.1] [1, p.2] |
| Official field 8822-B 6: New mailing address | Enter the complete new mailing address, including room or suite details. Do not abbreviate a foreign country name. | — | [1, p.1] [1, p.2] |
| Not attached to return | Form 8822-B is filed separately, rather than attached to a tax return. | — | [1, p.1] |
Read the requirements in context
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[3, p.3]
Name id matching
The name and identifying number on Form 7004 must match IRS records. A name mismatch or incorrect identifying number can invalidate the extension.[2, p.2]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Imagine a hypothetical LLC that has a retained Form 8822-B copy and information saying it was sent, while a later document still shows the earlier address. Annual preparation begins before anyone has clarified the processing status. The owner assembles a dated pack containing the original change details, the available submission information and the later correspondence. The old and requested new addresses retain their separate labels. The preparer records the actual uncertainty instead of silently updating the history to say that the IRS must now use the new address. If a Form 7004 draft contains current contact information, that draft is not treated as an additional account-update event. A question about the proper entry on a later filing is identified for the applicable instructions and appropriate review, rather than answered by whichever address appears most recently in the folder. This hypothetical pack allows the filing work and the update history to be discussed coherently. It does not establish processing, instruct the owner to send duplicate updates or promise that a preparation service can accelerate or guarantee a government change.[1, p.2] [2, p.2] [1, p.1]
Turn the records into a usable filing plan
Label the source and role of every item, distinguishing an owner's requested change, a preparation copy, information supporting submission and later correspondence. A message saying updated should be clarified if it could mean either the provider's internal file or the IRS record. Keep the uncertainty visible for the next preparer and identify who is following up the unresolved fact. If more information arrives, explain which question it answers without discarding the earlier sequence. SpeedEIN can assess the supported business-update task within its stated scope, but it should not be described as guaranteed IRS completion, automatic state updating or a way to make every later form update the master record. A clear pending pack supports careful preparation while respecting the distinction between a service's activity and the government's actual processing.[1, p.2] [2, p.2] [1, p.1]
Three checks before you proceed
- Which change document, submission information and later correspondence are actually available, with their dates and address roles?
- Has a new address on Form 7004 or an internal service file been kept separate from evidence of an IRS record update?
- Which address or processing question still requires applicable guidance or follow-up without assuming success or ordering an unsupported duplicate?
Related preparation guides
- Moving After Form 7004 but Before the Annual Return: Coordinate the Address Files
- You Cannot Find the Old IRS Address: Recover the Record Before Form 8822-B
- Closing the Address-Change File: Keep the Signed Form and the Source Records
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- Instructions for Form 7004 (Rev. December 2025) — Rev. December 2025
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.