SS-4 Lines 4–6: A Foreign Mailing Address and a Different Business Location
· 6 min read
The practical answer
The place where a company receives correspondence can differ from the place where the business operates. Preparing an address list first helps prevent a mailing arrangement from silently becoming an answer about the company's physical location. Three details shape the review: Where should company correspondence be received? Is the physical business location different? Are the foreign country and postal details complete? Keep each answer tied to the document or confirmed fact that supports it.[1, p.3] [2, p.1]
Scope and the records behind the answer
The discussion follows the entity, form and transaction conditions identified below. The same label on a different form can have a different purpose. Keep the relevant entity and reporting period visible while you compare the requirements, and treat each stated exception as part of the rule rather than an optional footnote.
Official sources checked: 2026-11-09. Annual tax-year forms and continuously revised forms are identified separately in the references.
A side-by-side preparation table
| Item or question | Official rule or instruction | Conditions and limits | Source |
|---|---|---|---|
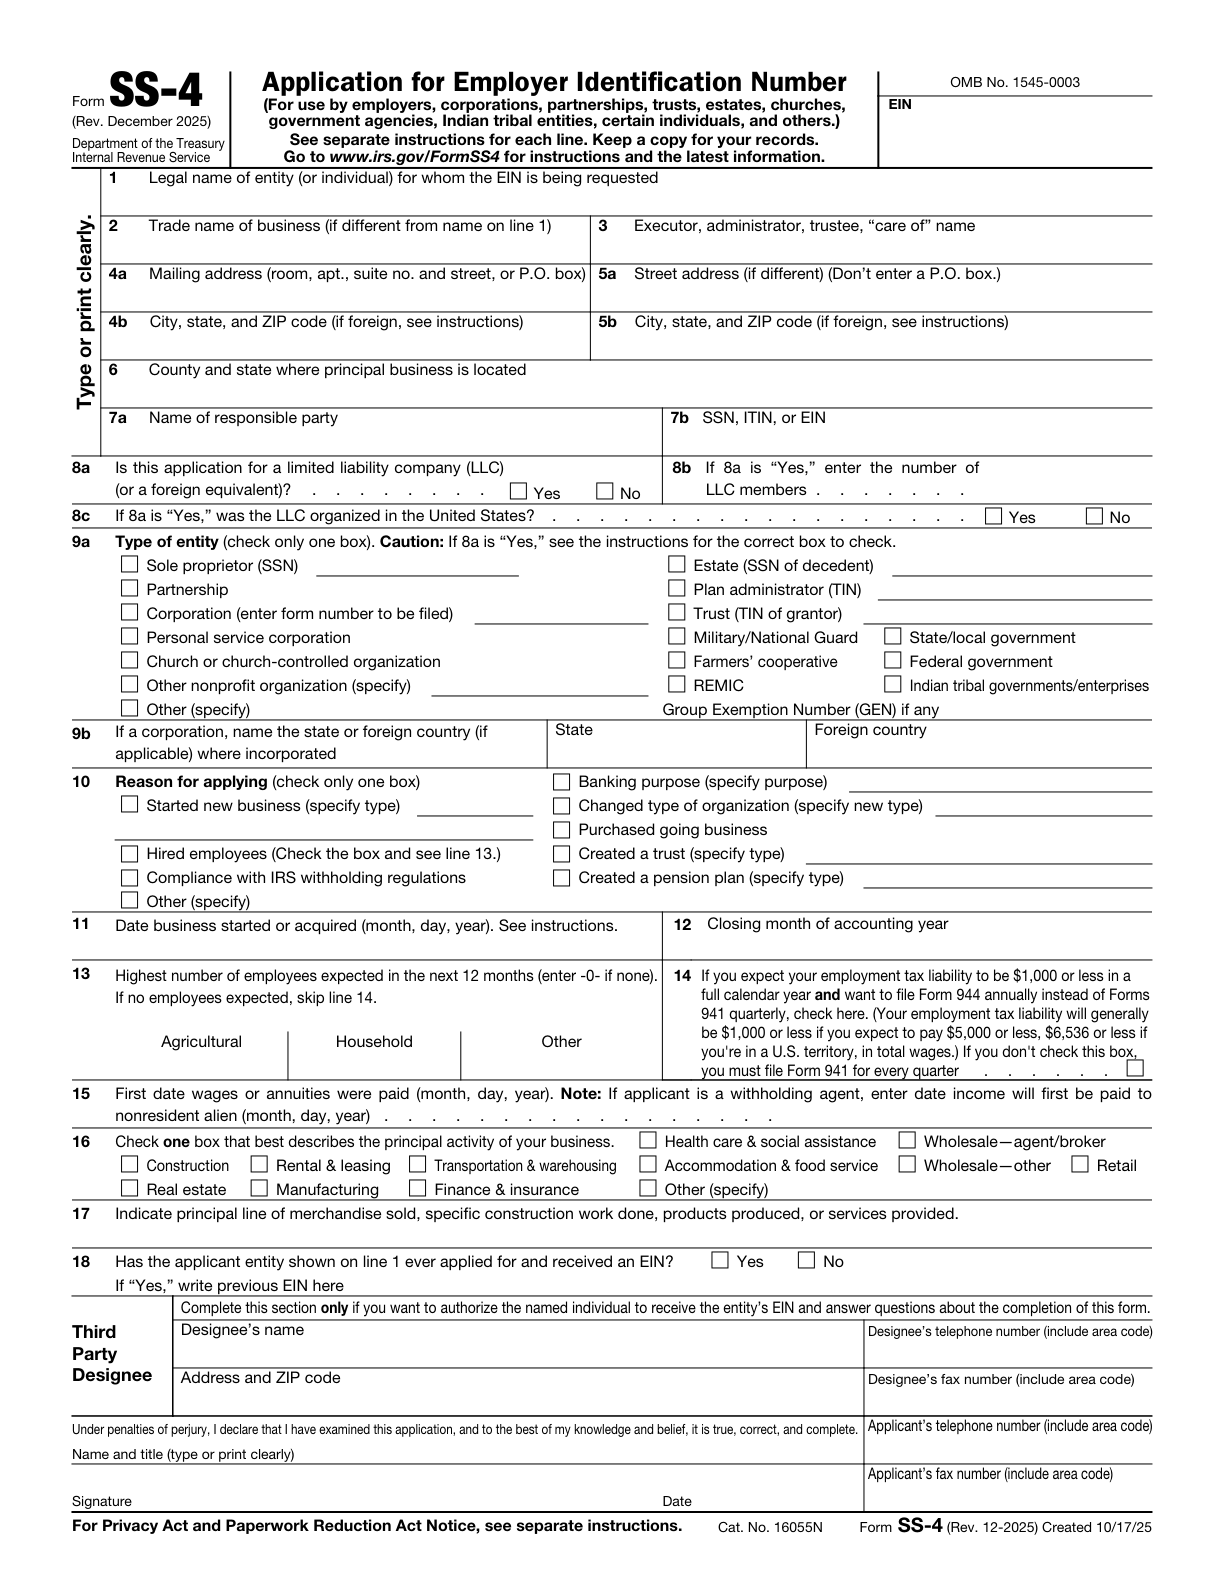
| Mailing address | Lines 4a-4b identify the mailing address where the entity receives correspondence. A foreign address must include the city, province or state, postal code and full country name. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [1, p.3] |
| Physical address | Complete lines 5a-5b only when the entity's physical address differs from its mailing address. Do not enter a P.O. box here. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [1, p.3] |
| Field/section 4a: Mailing address (room, apt., suite no. and street, or P.O. box) | Enter the mailing address for IRS correspondence, including room, suite and other applicable address details. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.1] [1, p.3] |
| Field/section 4b: City, state, and ZIP code (if foreign, see instructions) | For a foreign address, include the city, province or state, postal code and full country name. Do not abbreviate the country name. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.1] [1, p.3] |
| Field/section 5a: Street address (if different) (Don’t enter a P.O. box.) | Provide the physical address only if different from the mailing address. Do not enter a P.O. box here. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.1] [1, p.3] |
| Field/section 5b: City, state, and ZIP code (if foreign, see instructions) | Complete the city, province or state, postal code and foreign-country details for the physical address. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [2, p.1] [1, p.3] |
Work through the official requirements
Mailing address
Lines 4a-4b identify the mailing address where the entity receives correspondence. A foreign address must include the city, province or state, postal code and full country name.[1, p.3]
Physical address
Complete lines 5a-5b only when the entity's physical address differs from its mailing address. Do not enter a P.O. box here.[1, p.3]
Field/section 4a: Mailing address (room, apt., suite no. and street, or P.O. box)
Enter the mailing address for IRS correspondence, including room, suite and other applicable address details.[2, p.1] [1, p.3]
Field/section 4b: City, state, and ZIP code (if foreign, see instructions)
For a foreign address, include the city, province or state, postal code and full country name. Do not abbreviate the country name.[2, p.1] [1, p.3]
Field/section 5a: Street address (if different) (Don’t enter a P.O. box.)
Provide the physical address only if different from the mailing address. Do not enter a P.O. box here.[2, p.1] [1, p.3]
Field/section 5b: City, state, and ZIP code (if foreign, see instructions)
Complete the city, province or state, postal code and foreign-country details for the physical address.[2, p.1] [1, p.3]
Field/section 6: County and state where principal business is located
Identify the entity's principal physical business location. A mailing address does not automatically become its business location.[2, p.1] [1, p.3]
Authorized signer
The authorized SS-4 signer depends on the type of applicant. A foreign applicant may use a person with appropriate authorization to sign.[1, p.6]
Designee scope
The third-party designee may answer questions about the completed SS-4 and receive the new EIN. Signed authorization is required, and that authority ends when the EIN is assigned and released to the designee.[1, p.6]
An illustrative preparation scenario
In this hypothetical preparation example, a founder works from one country while a trusted contact receives company correspondence elsewhere. The draft repeats the contact's address in every field. A careful review compares the mailing instructions with the separate location information instead of treating them as one record. The preparer checks three points: Where should company correspondence be received? Is the physical business location different? Are the foreign country and postal details complete? The file remains a working comparison until the relevant facts and applicable instructions have been checked together. No agency outcome is assumed.[1, p.3] [2, p.1]
This is a planning illustration, not a statement that a particular filing has been accepted or that an entity qualifies for a tax result. Use the source-backed distinctions above to decide what information still needs to be established before a form is completed.
A review sequence you can actually use
- Where should company correspondence be received?
- Is the physical business location different?
- Are the foreign country and postal details complete?
Write down the answer and the record that supports it, rather than marking a question complete because a field contains text. When two records disagree, identify whether the difference concerns the entity, an individual, the reporting period or the type of change. That makes the remaining question specific enough to resolve against the relevant instruction.
Keep the scope of a preparation service separate from the government requirement. A service intake question may gather information for a workflow; it does not create an exception, extend a deadline or determine whether a transaction is reportable. The cited government material remains the basis for those conclusions.
Questions to settle before moving forward
How should I check field/section 4a: mailing address (room, apt., suite no. and street, or p.o. box)?
Enter the mailing address for IRS correspondence, including room, suite and other applicable address details. [2, p.1] [1, p.3]
How should I check field/section 4b: city, state, and zip code (if foreign, see instructions)?
For a foreign address, include the city, province or state, postal code and full country name. Do not abbreviate the country name. [2, p.1] [1, p.3]
How should I check field/section 5a: street address (if different) (don’t enter a p.o. box.)?
Provide the physical address only if different from the mailing address. Do not enter a P.O. box here. [2, p.1] [1, p.3]
How should I check field/section 5b: city, state, and zip code (if foreign, see instructions)?
Complete the city, province or state, postal code and foreign-country details for the physical address. [2, p.1] [1, p.3]
Official sources and versions
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Form SS-4 (Rev. December 2025) — Rev. December 2025
Get help with the relevant SpeedEIN workflow
SpeedEIN offers preparation and support for the situations described on its service pages. If you would like assistance, review the relevant service scope, supported entities and current availability before ordering. The service does not replace the government’s decision or remove an obligation imposed by the applicable rules.