A Name Change and an Address Change in One Project: Keep the IRS Procedures Separate
· 6 min read
The answer for this situation
A combined name-and-address project needs coordinated records but separate procedure questions. Form 8822-B's business-name field does not make it a general business-name-change application. Build two tracks: one for the applicable name-change procedure and one for the supported address, location or responsible-party update. Keep the before-and-after identity information linked so the same entity is not mistaken for two different businesses, while preserving any ownership or structural question that may change the analysis. A name or location change alone generally does not require a new EIN, but that rule should not be expanded into never needing one. The practical outcome is a clear combined project plan, not an assumption that one form, one service order or one state filing completes every federal task.[1, p.2] [2] [3]
Which facts change the answer?
The selected IRS corporate name-change route has conditions concerning federal tax classification, the applicable return and whether the current-year return has already been filed. It should not be applied to every state-law LLC merely because the entity has a company name. This article does not determine a DE's procedure from that corporate example, offer ordinary corporate or S-return preparation or resolve a simultaneous reorganization. If ownership or structure also changed, that issue needs its own relevant review. The supported business update remains subject to its actual route and separate-filing requirements.[1, p.2] [2] [3]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
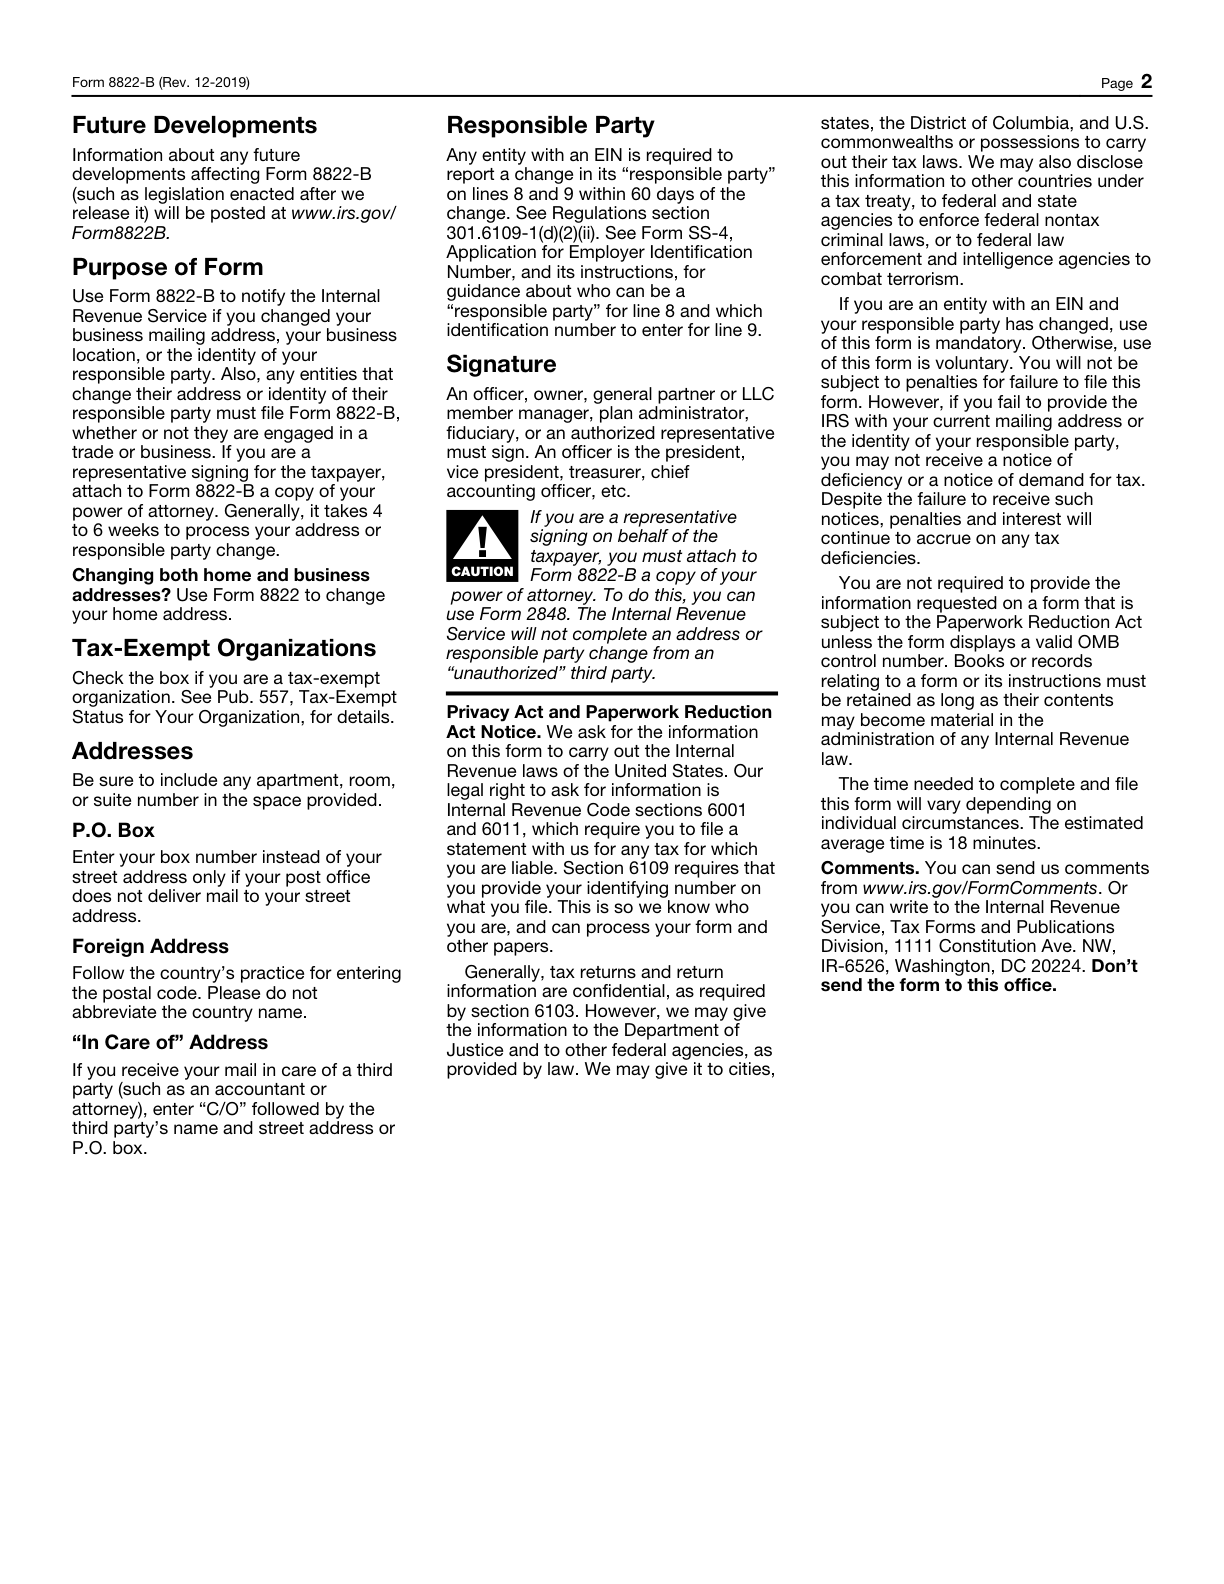
| Distinct from 8822b | A business-name-only change follows the IRS business-name-change procedure. The stated uses of Form 8822-B are changes to the business mailing address, business location or responsible party; its name field does not make it a general business-name-change application. | Distinguish a business name change from an address or responsible-party change. If several changes occur together, follow each applicable procedure. | [1, p.2] [2] |
| Purpose | Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. | — | [1, p.2] |
| Name only change no new ein | A name or location change alone generally does not require a new EIN. Ownership or structural changes require separate review. For LLCs, the IRS expressly lists changing the name or location among cases not requiring a new EIN. | Only the name or location changes, without an entity, ownership or structural event requiring a new EIN. If a reorganization, ownership change or entity-structure change also occurs, apply the rules for that entity type separately. Do not turn the name-change rule into a statement that a new EIN is never required. | [3] [2] |
| Corporation route | A corporation filing its current-year Form 1120 may indicate a name change in page 1, item E, box 3. If that year's return has already been filed, send a letter signed by a corporate officer to the address where the return was filed. The Form 1120-S name-change box is instead item H, box 2. | The entity is classified as a corporation for federal tax purposes and files the applicable Form 1120-series return. Select the route according to whether the current-year return has already been filed. Do not apply the corporation route to every state-law LLC. Determine its federal tax classification and applicable guidance first. | [2] |
| Route old address | The Form 8822-B mailing destination is selected using the old business address, rather than the new address or the state of formation alone. | — | [1, p.1] |
| Not attached to return | Form 8822-B is filed separately, rather than attached to a tax return. | — | [1, p.1] |
Read the requirements in context
Official field 8822-B 4a: Business name
Enter the current business name. This form is not a company-name-change application.[1, p.1]
Official field 8822-B 4b: Employer identification number
Enter the business's EIN.[1, p.1]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Suppose a hypothetical owner changes an LLC's name and business mailing arrangement in one administrative project. The owner supplies updated state information and asks a provider to complete the IRS change on Form 8822-B. The working plan first identifies which facts concern the new name and which concern the business address. The name-change track asks what federal tax classification and applicable official guidance govern that task, rather than automatically using the corporate-return box shown in another guide. The address track retains the old business address for its route question and records the proposed new mailing information separately. The existing EIN remains linked to the entity history while any ownership or structural event is identified for separate review; a new application is not ordered solely to make the new name look consistent. Each track has its own preparation and submission status. This hypothetical plan coordinates identity information without declaring that the state update changed IRS records, that Form 8822-B completed the name procedure or that a corporate or S-return service has been accepted.[1, p.2] [2] [3]
Turn the records into a usable filing plan
Before authorizing work, ask which precise task each provider is undertaking and which official procedure remains to be confirmed. Keep original records identifiable and use a cross-reference to connect the old and new names, rather than overwriting the historical address or entity information. A current-name entry on the business form should not be used as proof that a separate name-change procedure was completed. Where the classification context is unclear, preserve that question instead of copying another entity type's route. SpeedEIN's supported IRS business-update assistance should be described within its stated change scope, without implying that it covers every name procedure, a structural reorganization or automatic state updates. The useful service discussion is a bounded task on one track, coordinated with the independently established work on the other.[1, p.2] [2] [3]
Three checks before you proceed
- Which parts of the project concern the name procedure and which concern the supported business-address or other update?
- Does the chosen name route match the actual federal classification and filing context rather than the state-law LLC label alone?
- Have any ownership or structural changes and the existing EIN history been reviewed separately from a name-only or location-only change?
Related preparation guides
- Your Home Address and the LLC's Address Both Changed: Separate Personal and Business Records
- An IRS Address Update Is Still Pending When Filing Work Starts: Preserve Both Records
- A Business Name Change Requires a Different IRS Update From Form 8822-B
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- Business name change
- When to get a new EIN
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.