A W-8 Certificate Expires or Becomes Incorrect: That Does Not Replace the EIN Record
· 6 min read
The answer for this situation
A message saying your tax form has expired can sound as though the business has lost its tax number. Before paying for another EIN application, identify the document named in the request. The validity of a foreign-status certificate and the continuing existence of an assigned EIN are different questions. A certificate can require replacement because time has passed or its information is no longer correct, while the entity still has the same identifier. The practical response is a two-track record: one track shows the company's EIN and identity history; the other shows the certificate, its recipient and the facts on which it was based.[1, p.3] [2, p.1] [3]
Which facts change the answer?
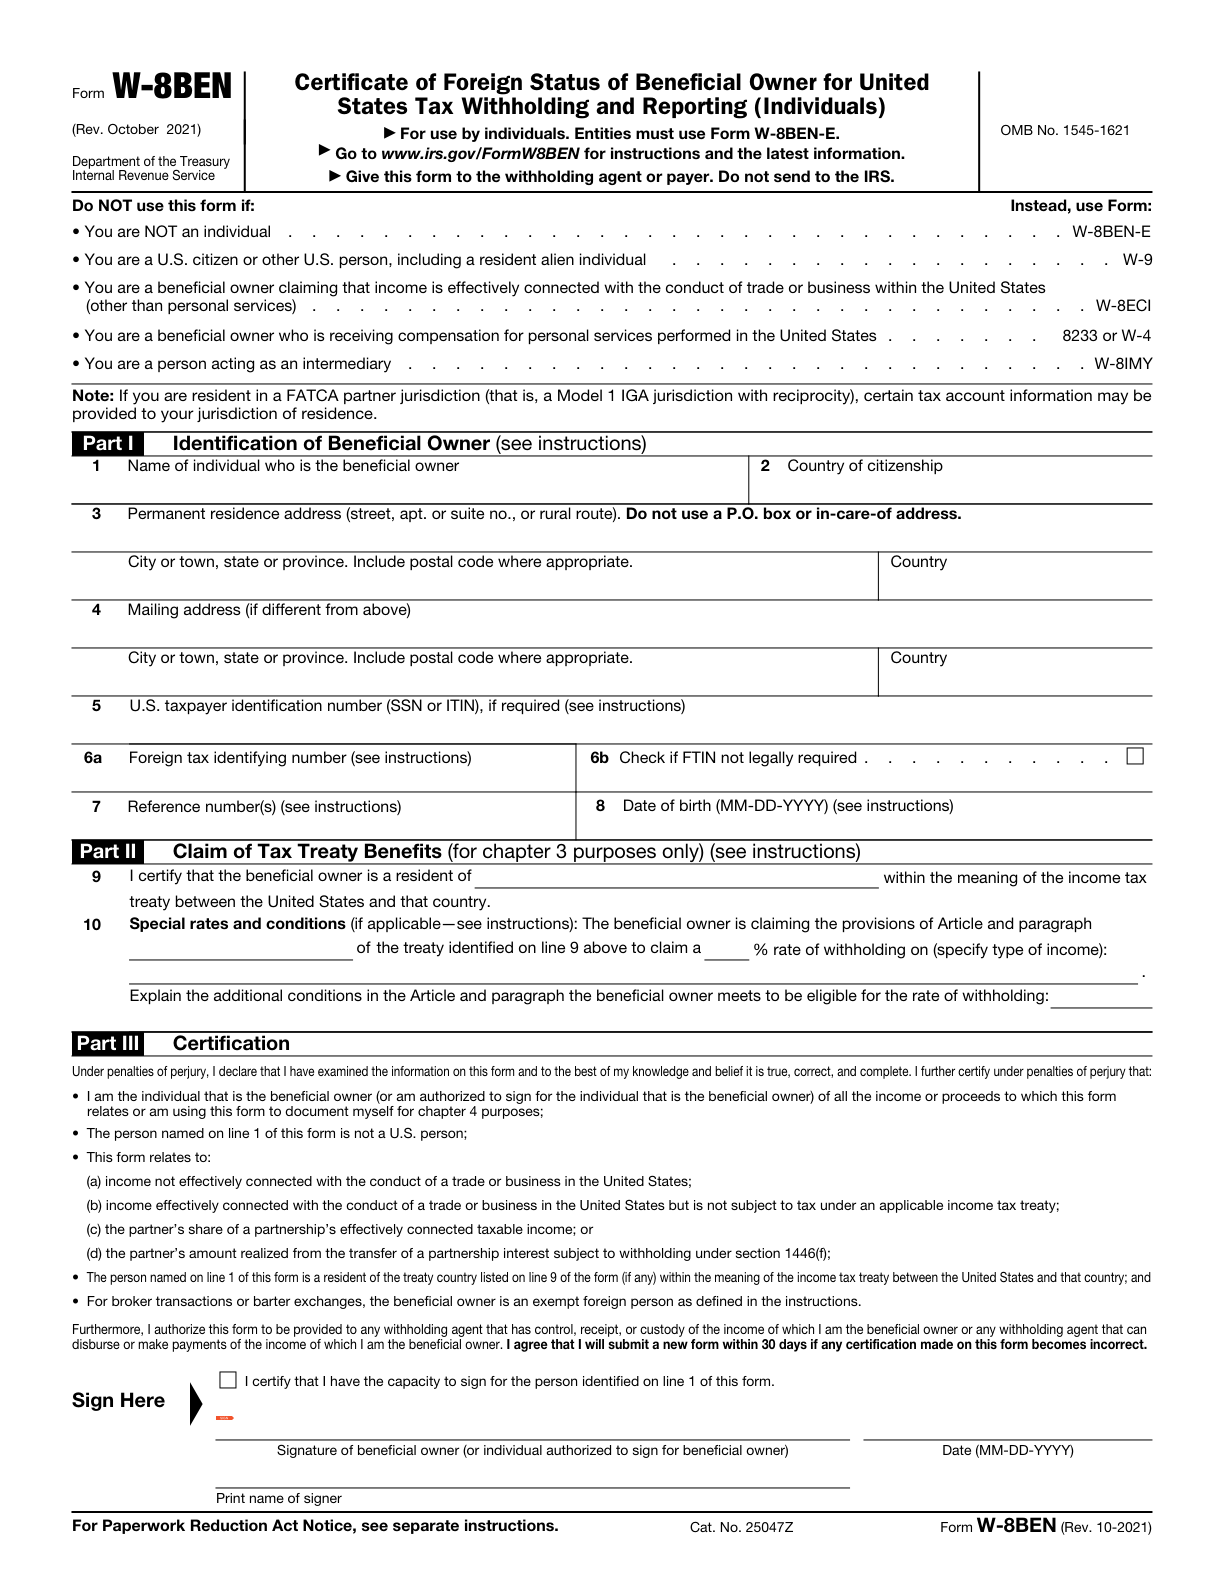
The ordinary W-8BEN foreign-status validity rule runs from signing through the end of the third succeeding calendar year, unless a change in circumstances makes information incorrect. The instructions also contain qualifications and continuing-validity rules for particular situations, so that ordinary period is not universal. Where changed circumstances make the form incorrect, the relevant instruction requires notification to the withholding agent or payer within 30 days and the applicable replacement documentation. Do not confuse this recipient-specific task with the Form 8822-B responsible-party rule or assume either action cancels the other. An assigned EIN is the entity's permanent federal taxpayer identifier, although separate changes can still need review.[1, p.3] [2, p.1] [3]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| General validity | For establishing foreign status, Form W-8BEN generally remains in effect from signature through the last day of the third succeeding calendar year, unless a change in circumstances makes information incorrect; the instructions contain additional conditions and exceptions. | Under certain conditions the form remains effective indefinitely until a change in circumstances. The instructions reference separate chapter 3 and chapter 4 validity rules; the general period is not universal. | [1, p.3] |
| Change 30 days | If a change in circumstances makes information on a submitted Form W-8BEN incorrect, notify the withholding agent, payer or FFI holding the account within 30 days of that change and provide a new Form W-8BEN or other appropriate form. | The instructions distinguish moves to the United States, moves between foreign addresses and treaty-related residence changes; not every address change has the same effect. | [2, p.1] [1, p.3] |
| Ein deactivation not cancel | The IRS says an EIN cannot be cancelled, although it can be deactivated; once assigned to an entity it is that entity’s permanent federal taxpayer ID. | State dissolution is a separate agency action, not an automatic IRS deactivation. | [3] |
| Purpose | Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. | — | [4, p.2] |
| Name only change no new ein | A name or location change alone generally does not require a new EIN. Ownership or structural changes require separate review. For LLCs, the IRS expressly lists changing the name or location among cases not requiring a new EIN. | Only the name or location changes, without an entity, ownership or structural event requiring a new EIN. If a reorganization, ownership change or entity-structure change also occurs, apply the rules for that entity type separately. Do not turn the name-change rule into a statement that a new EIN is never required. | [5] [6] |
| Recipient not irs | Give Form W-8BEN to the withholding agent or payer requesting it; do not send it to the IRS. | — | [2, p.1] |
Read the requirements in context
Us person uses w9
A U.S. person, including a resident alien individual within the instructions, uses Form W-9 rather than certifying foreign status on Form W-8BEN.[2, p.1]
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[7, p.3]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Suppose a hypothetical owner, Aiko, receives a reminder from a payer about an older W-8BEN. She also moved during the year. Her initial note says renew business tax number, which mixes the documents before anyone has examined them. Aiko changes the task label to review payer certificate and retrieves the signed certificate, the payer's message and her current facts. In the certificate track, she records the signature date, the stated purpose and whether an address or status change made any information incorrect earlier than an ordinary expiry date. In the EIN track, she retains the company's assignment letter and identifies whether a separate business mailing-address update is actually needed. She does not apply one calendar date to both tracks. If the changed facts raise a U.S.-person question, she stops copying the old foreign-status certification and asks for the applicable documentation review. If the issue is simply an ordinary certificate-validity request, that does not itself demonstrate that the LLC needs another EIN. The resulting handoff has a named payer-documentation action, a separately assessed business-record action and an unchanged identity reference where appropriate. It does not pronounce on a particular payer's acceptance or make the old certificate valid merely because a new draft has been prepared.[1, p.3] [2, p.1] [3]
Turn the records into a usable filing plan
Use the actual certificate and request when discussing the issue, rather than describing every document as an EIN form. Keep the original certificate facts, the reason for review and the replacement or notification record together. A date reminder is useful, but a calendar cannot detect an ownership, residence or other factual change unless someone records it. SpeedEIN's business-update service concerns the supported IRS address, location or responsible-party changes; it does not automatically update every payer's certificate. Its EIN service should not be purchased as a routine renewal of an assigned number. Where the company itself changed ownership or structure, examine that separate question instead of treating this guide as a no-new-EIN ruling for every transaction.[1, p.3] [2, p.1] [3]
Three checks before you proceed
- Which exact document does the reminder identify, and who issued the request?
- Did information become incorrect before the ordinary certificate-validity period ended?
- Have you separated the payer notification, any IRS update and the existing EIN record?
Related preparation guides
- An EIN Application, Form 5472 and a W-8 Certificate Go to Different Recipients
- Buying an Existing LLC: Review the IRS Records Before Ordering a Routine Update
- After Moving: Check Whether the EIN Itself Still Applies
Official sources and document versions
Official source versions checked: 2026-11-10
- Instructions for Form W-8BEN (Rev. October 2021) — Rev. October 2021
- Form W-8 BEN (Rev. October 2021) — Rev. October 2021
- If you no longer need your EIN
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- When to get a new EIN
- Business name change
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.