An EIN Application, Form 5472 and a W-8 Certificate Go to Different Recipients
· 6 min read
The answer for this situation
A folder can contain every document someone has requested and still fail to show what has actually been delivered. Owners often collect the EIN application, a payer's W-8 request and the annual Form 5472 material in the same place. That is convenient for storage, but it can conceal three different destinations. The practical first question is who is asking for each item and what action that recipient is expected to take. Build a routing map before preparing a combined upload or mailing. It should show the document, the taxpayer or certifying person, the recipient and the evidence that the intended delivery happened.[1, p.1] [2, p.2] [3, p.6]
Which facts change the answer?
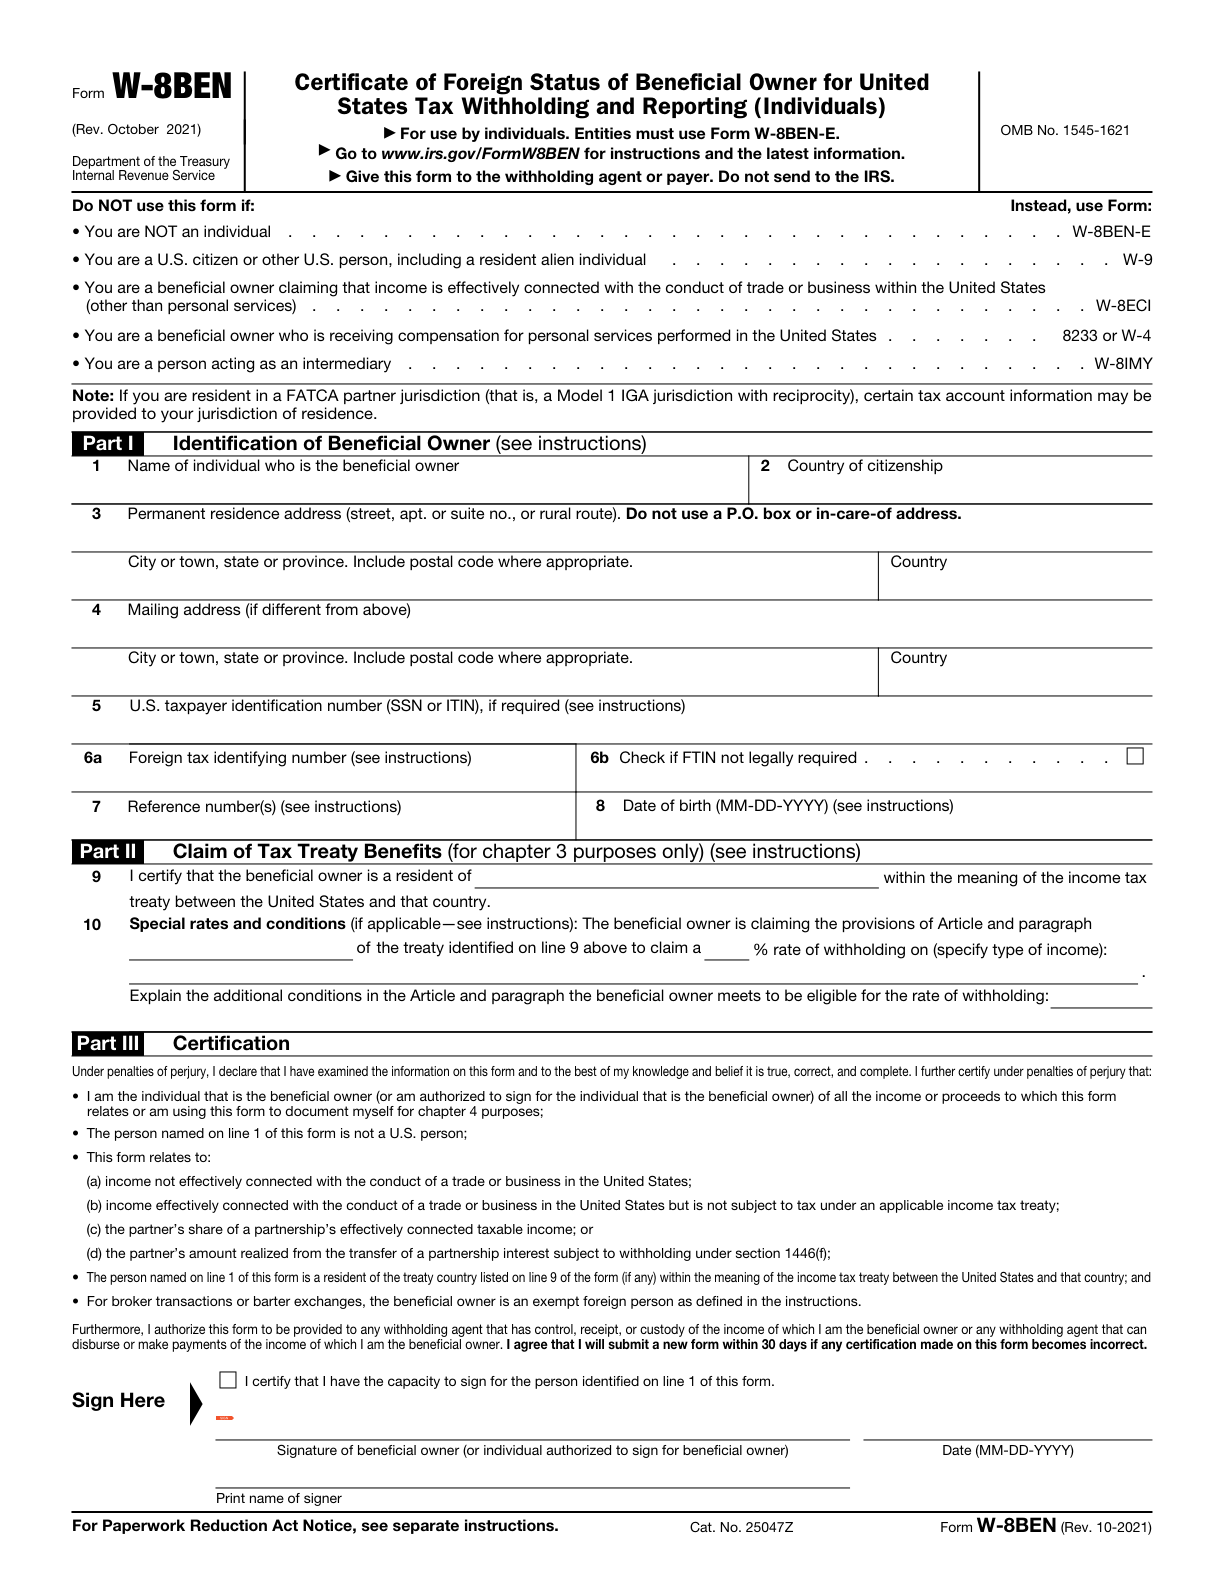
Form W-8BEN is generally given to the withholding agent or payer requesting it, rather than sent to the IRS. The foreign-owned U.S. disregarded-entity Form 5472 package follows its own IRS submission instructions and includes the specified pro forma Form 1120. An SS-4 designee's authority concerns the application and receipt of the new EIN; that authority does not turn the designee into the continuing recipient for every tax document. These distinctions do not establish that a particular owner should use W-8BEN. A U.S. person or a different ownership structure requires the applicable documentation review first.[1, p.1] [2, p.2] [3, p.6]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Recipient not irs | Give Form W-8BEN to the withholding agent or payer requesting it; do not send it to the IRS. | — | [1, p.1] |
| De proforma required | A foreign-owned U.S. DE subject to Form 5472 filing attaches Form 5472 to a pro forma Form 1120 and files by the Form 1120 due date, including a valid extension. | — | [2, p.2] |
| Designee scope | The third-party designee may answer questions about the completed SS-4 and receive the new EIN. Signed authorization is required, and that authority ends when the EIN is assigned and released to the designee. | — | [3, p.6] |
| Individual owner de | For a payment within the scope of Form W-8BEN, a foreign individual who solely owns a disregarded entity not claiming treaty benefits as a hybrid entity completes the form with the individual owner’s name and information. If the payment account is in the disregarded entity’s name, inform the withholding agent. | The payment must be within the applicable scope of Form W-8BEN. The entity is not claiming treaty benefits as a hybrid entity. | [4, p.6] |
| Reportable transaction trigger | A reporting corporation generally files Form 5472 when it has a reportable transaction with a foreign or U.S. related party during the tax year. Operating revenue alone does not determine the filing requirement. | — | [2, p.2] |
| De mail route | A foreign-owned U.S. DE uses the special PIN Unit mailing route in the Form 5472 instructions, rather than the ordinary Form 1120 mailing addresses. | Applies to the Form 5472/pro forma Form 1120 package for a foreign-owned U.S. DE. | [2, p.2] |
Read the requirements in context
Us person uses w9
A U.S. person, including a resident alien individual within the instructions, uses Form W-9 rather than certifying foreign status on Form W-8BEN.[1, p.1]
Foreign owned us de definition
A foreign-owned U.S. disregarded entity is a domestic disregarded entity wholly owned by a foreign person. Its treatment as a corporation for these purposes is limited to the reporting requirements related to section 6038A.[2, p.2]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Imagine a hypothetical software designer, Mateo, whose LLC has recently received its EIN. A customer asks him for foreign-status documentation, and a separate reminder says that annual-filing records are needed. He creates one folder called IRS documents and plans to send everything to the preparer. The preparer would then have files without a clear instruction about which task is authorized. Mateo instead gives each item a destination label. The EIN letter becomes an identity source. The customer's actual certificate request is assigned to a payer-documentation task. The transaction schedule and annual form data belong to the information-return task. He records who must decide the certificate question, who is preparing the annual packet and who will keep the submitted copies. A document can be shared as a reference without treating that share as its official submission. His map also distinguishes draft, supplied for review and delivered to the intended recipient. If he uploads a certificate to the preparer's conversation, that alone does not demonstrate that the customer received it. Equally, sending company details to a customer does not demonstrate that the IRS received an annual package. The useful output is a small set of verified destinations and open actions, rather than a large folder whose contents all carry an ambiguous completed label.[1, p.1] [2, p.2] [3, p.6]
Turn the records into a usable filing plan
Ask the person handling each task to identify the deliverable and destination in plain language. For an annual package, retain the as-submitted documents and appropriate delivery evidence under the applicable filing route. For a payer certificate, keep the request and the record of what was supplied to that payer; this organizational advice does not create a new IRS attachment requirement. SpeedEIN's EIN and supported annual-filing services should be assessed as separate scopes of work. Do not assume that ordering one includes certificate preparation, personal tax work or continuing representation. A routing question should be resolved before sensitive information is sent to an unintended recipient, not after a combined packet has already left.[1, p.1] [2, p.2] [3, p.6]
Three checks before you proceed
- Who requested each document, and which recipient is actually supposed to receive it?
- Does the status mean draft, reviewed or delivered to the intended destination?
- Have the EIN application, payer certification and annual filing been assigned separate deliverables?
Related preparation guides
- The Owner or the LLC? Identify Who Is Certifying Foreign Status After the EIN Arrives
- An EIN Does Not Approve Treaty Benefits: Separate Assignment From Tax Certification
- After EIN Assignment: Build Separate Files for IRS Changes and Annual Reporting
Official sources and document versions
Official source versions checked: 2026-11-10
- Form W-8 BEN (Rev. October 2021) — Rev. October 2021
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Instructions for Form W-8BEN (Rev. October 2021) — Rev. October 2021
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.