Does the LLC's EIN Create a Personal ITIN Requirement? Identify the Separate Tax Purpose
· 6 min read
The answer for this situation
An owner completing an LLC project may be told that the next step is to obtain a personal ITIN. Sometimes that advice is based only on the existence of the company's EIN, rather than a particular personal tax requirement. Start by asking which document needs whose number and for what purpose. An EIN assignment does not, by itself, answer every owner-identification question on every later form. A useful preparation sheet lists the entity's EIN separately from the owner's existing U.S. number, foreign tax number and any form-specific reference ID. The goal is to find the actual missing dependency, not to collect identifiers simply because they appear in the same business folder.[1, p.1] [2, p.2] [3, p.3]
Which facts change the answer?
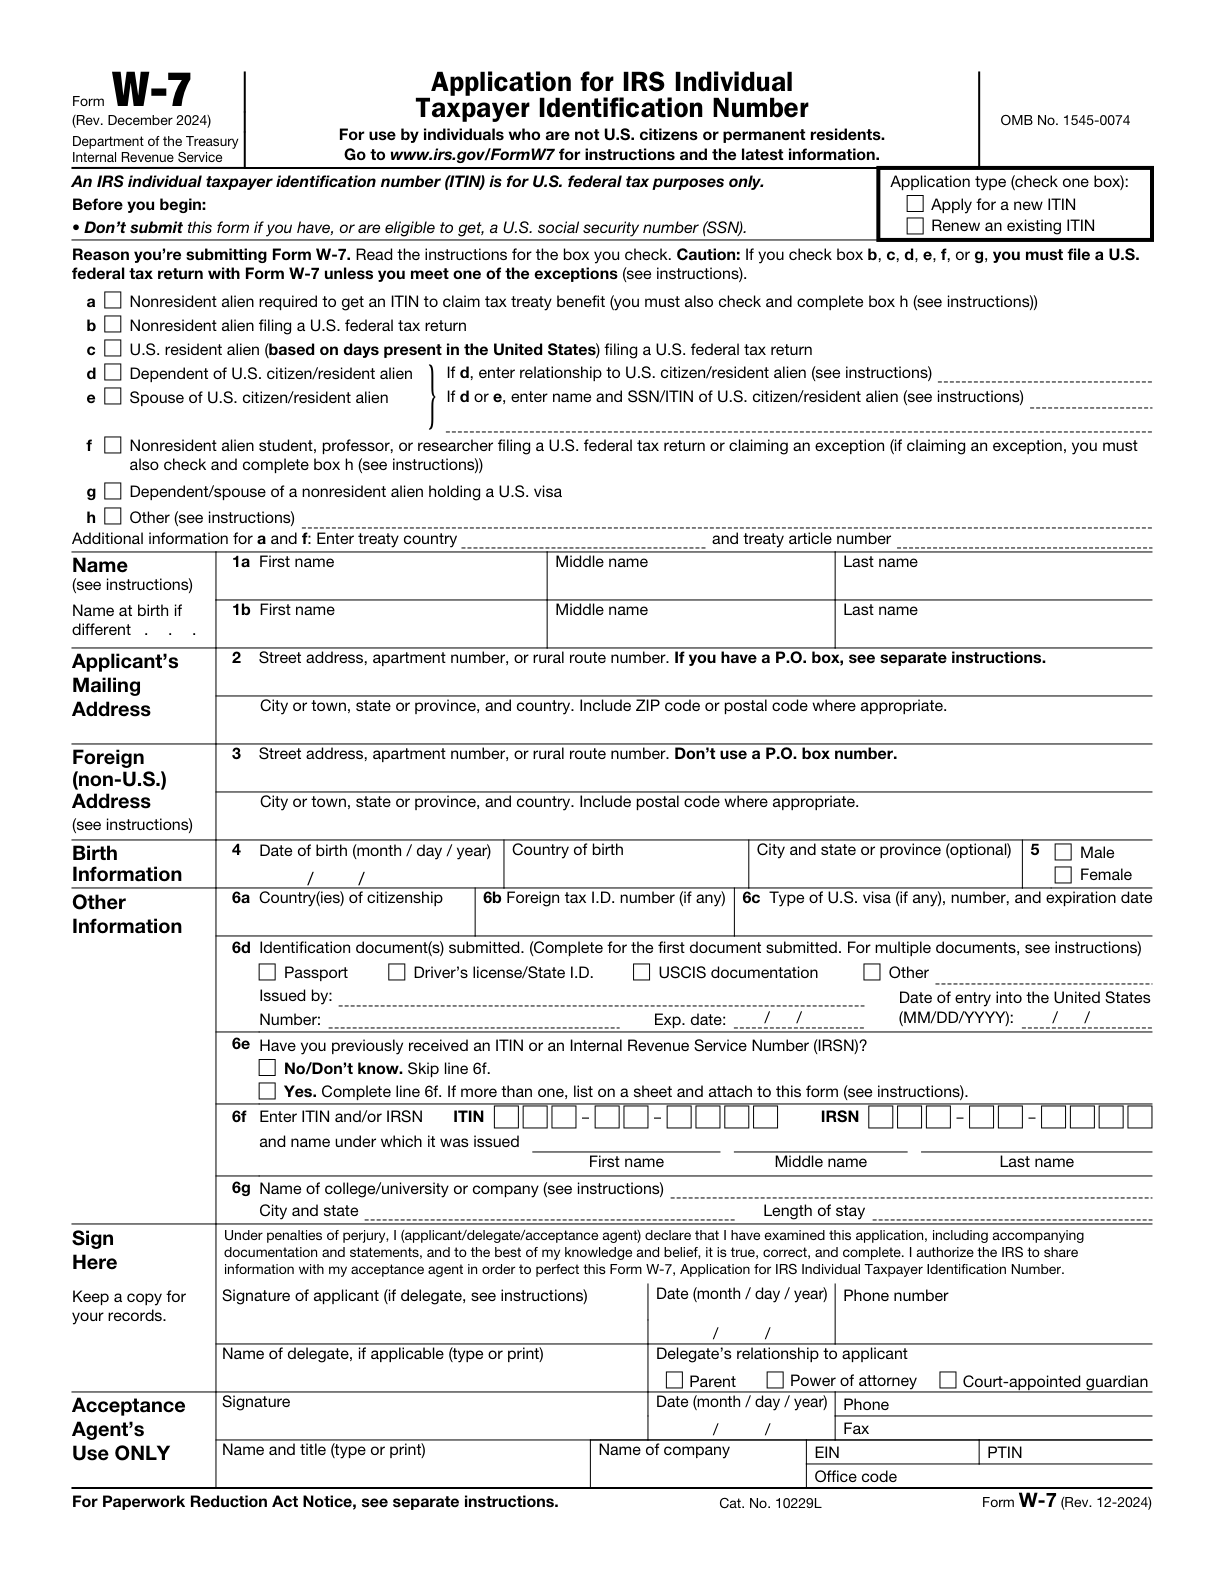
An ITIN is for U.S. federal tax purposes only and does not change immigration status or the right to work in the United States. A person eligible for an SSN does not simply choose an ITIN instead under the W-7 instructions. Other forms have their own conditions: the SS-4 line 7b foreign or N/A entry depends on both not having and being ineligible to obtain an SSN or ITIN, while Form 8832 and Form 5472 have different owner-ID instructions. None of these examples should be turned into a universal rule that an owner always needs, or never needs, an ITIN. The personal tax question must be identified independently. The W-7 exclusion also applies to someone who already has an SSN, not only someone who could obtain one.[1, p.1] [2, p.2] [3, p.3]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Federal tax purpose | An ITIN is for U.S. federal tax purposes only. Obtaining an ITIN does not change immigration status or the right to work in the United States. | — | [1, p.1] [2, p.2] |
| Ssn eligibility exclusion | Do not submit Form W-7 if you already have, or are eligible to obtain, a U.S. Social Security number (SSN). | — | [1, p.1] |
| Id exception | Enter foreign or N/A on line 7b only when the responsible party neither has nor is eligible to obtain an SSN or ITIN. The line must contain an entry. | The responsible party does not have an SSN or ITIN. The responsible party is not eligible to obtain an SSN or ITIN. | [3, p.3] |
| Ein required | Form 8832 requires the entity's own EIN; Applied For is not accepted. An entity that already has an EIN retains that EIN after a classification change. | — | [4, p.7] |
| Reference id when missing us id | When the applicable foreign shareholder has no U.S. identifying number entered in Part II, use the reference ID required by the instructions. The reporting entity or its representative creates this ID; it is not a separate IRS application. | — | [5, p.4] |
| De ftin none | A foreign-owned U.S. DE reports its direct and ultimate foreign owners' FTINs, if any. If an owner has no FTIN, enter "None" or "N/A" in that field. Different reporting-entity rules must be checked separately. | Foreign-owned U.S. disregarded entity. | [5, p.5] |
Read the requirements in context
Individual owner de
For a payment within the scope of Form W-8BEN, a foreign individual who solely owns a disregarded entity not claiming treaty benefits as a hybrid entity completes the form with the individual owner’s name and information. If the payment account is in the disregarded entity’s name, inform the withholding agent.[6, p.6]
When this applies: The payment must be within the applicable scope of Form W-8BEN. The entity is not claiming treaty benefits as a hybrid entity.
Foreign owned us de definition
A foreign-owned U.S. disregarded entity is a domestic disregarded entity wholly owned by a foreign person. Its treatment as a corporation for these purposes is limited to the reporting requirements related to section 6038A.[5, p.2]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Consider a hypothetical owner, Dev, who receives an EIN letter for North Loom LLC. A checklist from an earlier adviser says personal tax ID, but it does not name a return or explain the relevant requirement. Dev should not replace the phrase with either apply for ITIN or write foreign everywhere. He creates a request sheet with the actual form, the person identified by the field, the number already available and the reason the requester believes another identifier is needed. The company's EIN belongs in its entity row. His personal U.S.-number question belongs in a different row, while any foreign tax number is identified as such rather than relabelled as an ITIN. Where the current job involves Form 5472, he checks its own identifying-number and reference-ID instructions. Where it involves an EIN application, the particular SS-4 exception must be evaluated on its stated conditions. If a personal federal return or another tax purpose is the real issue, he takes that specific question to the appropriate adviser. The file makes clear what remains undecided without pretending that the company's paperwork has resolved his personal tax position or immigration circumstances.[1, p.1] [2, p.2] [3, p.3]
Turn the records into a usable filing plan
Ask for the form name and the exact identification field whenever someone says an ITIN is required. Keep an existing SSN or ITIN distinct from an EIN, a foreign number and an internally assigned reference ID. Do not use a missing-number exception simply because another form allowed a different entry. SpeedEIN's business services should be chosen for the supported application, information-return or update work actually needed; this guide does not offer ITIN, CAA or personal-return preparation. If an owner-identification fact affects the business filing, disclose it accurately before preparation. Resolve the separate personal tax purpose and any SSN-eligibility question through the relevant official instructions and qualified advice instead of adding an unnecessary application to the LLC project.[1, p.1] [2, p.2] [3, p.3]
Three checks before you proceed
- Which exact form and field are said to require the owner's personal identifier?
- Have the EIN, personal U.S. number, FTIN and reference ID remained clearly distinct?
- Has the separate federal tax purpose and any SSN eligibility been reviewed rather than assumed?
Related preparation guides
- Company Documents Show Different Numbers: Map Each IRS Form to the Correct Identifier
- Foreign, None, N/A or a Reference ID? Missing-Number Instructions Differ by Form
- If the Responsible Party Already Has an ITIN: Keep It Separate From the LLC’s EIN
Official sources and document versions
Official source versions checked: 2026-11-10
- Form W-7 (Rev. December 2024) — Rev. December 2024
- Instructions for Form W-7 (Rev. December 2024) — Rev. December 2024
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Instructions for Form W-8BEN (Rev. October 2021) — Rev. October 2021
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.