First-Time Abatement: The Limited 5472 Procedure Is Not a General Promise
· 8 min read
The practical answer
A familiar relief label can create expectations before the specific penalty procedure has been checked. For a Form 5472 case, identify the assessment route and the linked return history before treating a limited internal procedure as a general promise to every filer. Three details shape the review: Which penalty and processing route are involved? Does the associated return history meet the specific conditions? Is a limited procedure being generalized beyond its scope?[1] [2] [3, p.3]
Scope and the records behind the answer
The discussion follows the entity, form and transaction conditions identified below. The same label on a different form can have a different purpose. Keep the relevant entity and reporting period visible while you compare the requirements, and treat each stated exception as part of the rule rather than an optional footnote.
Official sources checked: 2026-11-09. Annual tax-year forms and continuously revised forms are identified separately in the references.
A side-by-side preparation table
| Item or question | Official rule or instruction | Conditions and limits | Source |
|---|---|---|---|
| Prn711 fta limited procedure | There is no general guaranteed first-time abatement for Form 5472. The IRM describes a limited procedure for an initial, system-assessed PRN 711 penalty on Form 5472 attached to a late Form 1120, linked to the related Form 1120's first-time-abatement eligibility and additional three-period conditions. | Form 5472 was attached to a late Form 1120 and generated an initial system-assessed PRN 711 penalty. The associated Form 1120 late-filing penalty received first-time abatement under PRC 018, or no such penalty was assessed because tax was zero or fully paid but the return otherwise could have qualified for that abatement. There were no similar PRN 625/711 penalties in the preceding three periods. The associated Forms 1120 were not late in the preceding three periods. Do not generalize this procedure to all Form 5472 penalties, all foreign-owned DEs, continuing-failure penalties or other PRNs. The procedure says may be abated; applicable facts and IRS action are still required. | [1] |
| Reasonable cause case by case | Reasonable cause and good faith are evaluated case by case using all relevant facts. Reliance on an accountant, attorney or another professional does not necessarily establish them; that reliance must be reasonable under all the circumstances. | The IRS is reviewing reasonable cause and good faith for a section 6038A failure. | [2] |
| Failure penalty | Failure to file Form 5472 at the prescribed time and in the prescribed manner, or to maintain required records, can result in a $25,000 penalty. A substantially incomplete form is treated as a failure to file. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [3, p.3] |
| Cp215 assessment notice | The Form 5472 IRM procedure states that an assessment using MFT 13 and PRN 625 generates and sends a BMF CP 215 penalty notice. This is a post-assessment procedure. | This concerns an MFT 13/PRN 625 assessment under IRM 20.1.9.5.2. Different processing routes may use different PRNs; this does not establish one identical notice code for every Form 5472 case. | [1] |
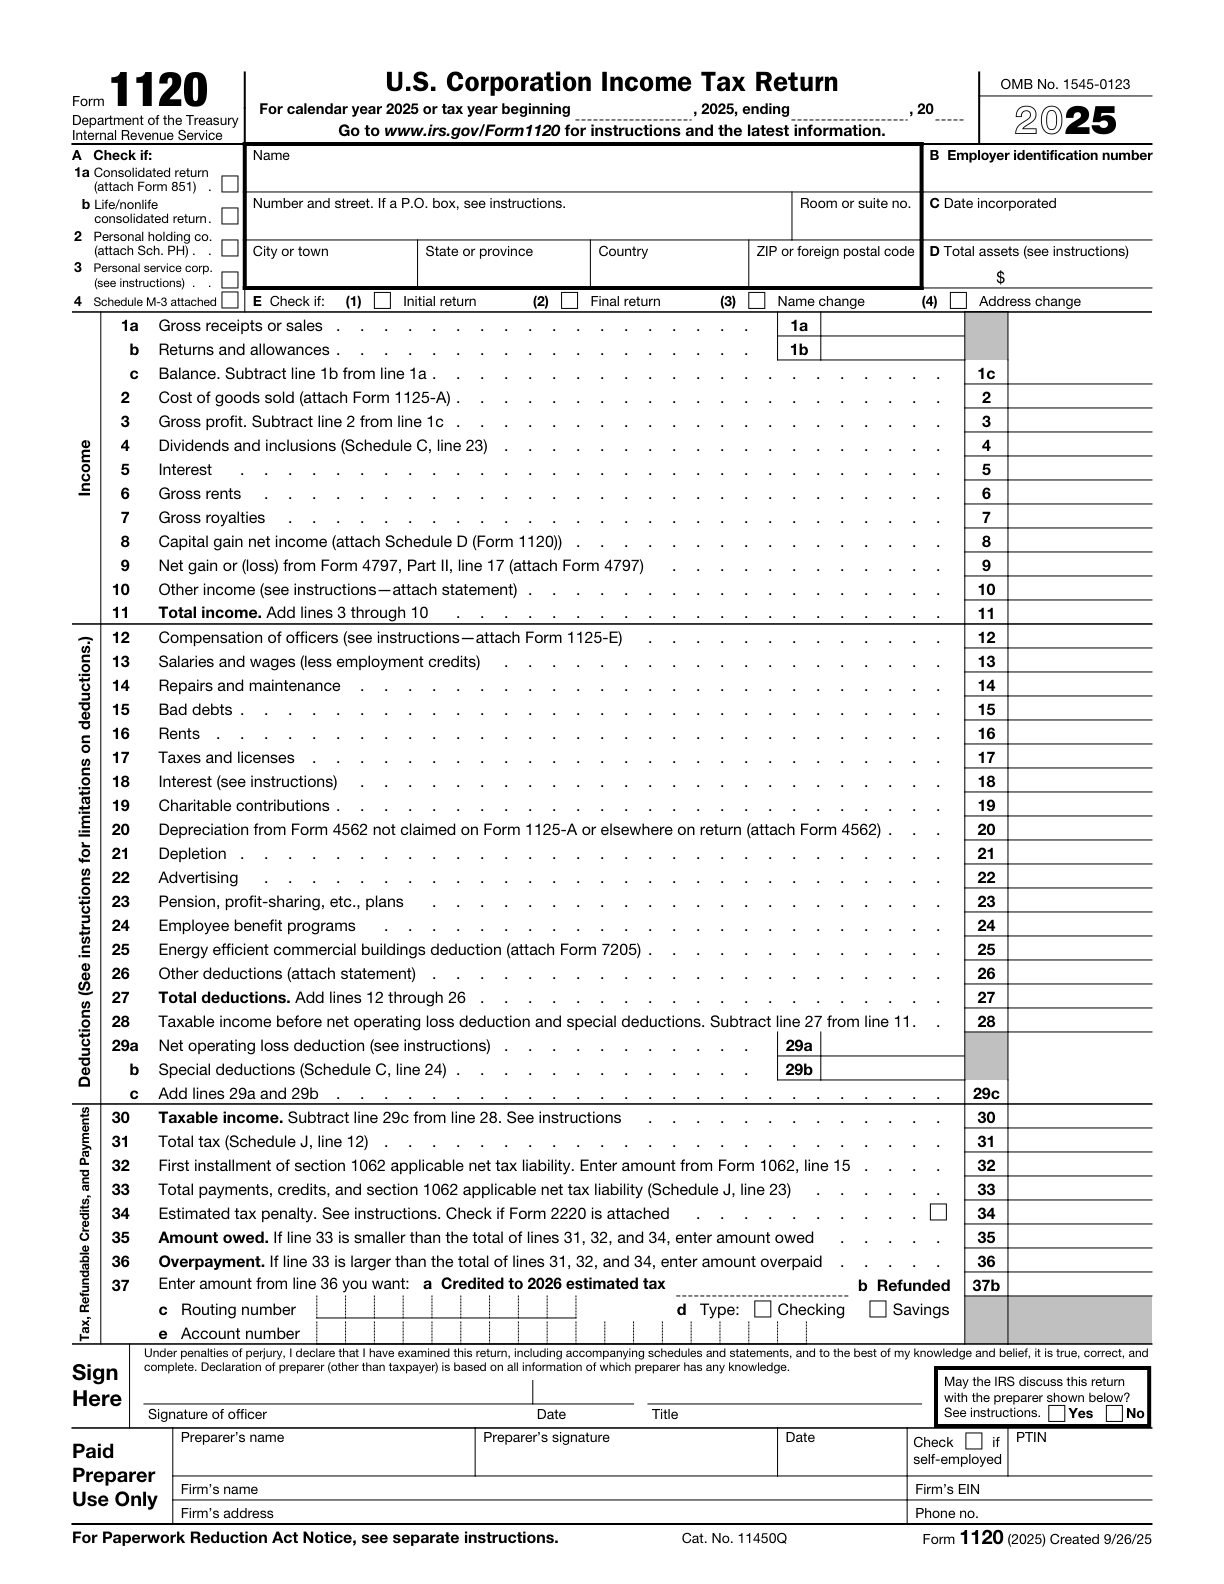
| Field/section E(4): Address change | Use the applicable item E box when the address changed. This does not replace a separate address-change procedure that is required. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [4, p.1] [3, p.2] |
| Field/section Part II heading: surrogate foreign corporation under section 7874(a)(2)(B) | Check this only when the inversion or surrogate-foreign-corporation rules in the Part II heading apply. It is not a general foreign-shareholder checkbox. | Apply this entry within the entity, form and period described here; read the cited passage for the surrounding context. | [5, p.1] [3, p.4] |
Work through the official requirements
Prn711 fta limited procedure
There is no general guaranteed first-time abatement for Form 5472. The IRM describes a limited procedure for an initial, system-assessed PRN 711 penalty on Form 5472 attached to a late Form 1120, linked to the related Form 1120's first-time-abatement eligibility and additional three-period conditions.[1]
This applies when: Form 5472 was attached to a late Form 1120 and generated an initial system-assessed PRN 711 penalty. The associated Form 1120 late-filing penalty received first-time abatement under PRC 018, or no such penalty was assessed because tax was zero or fully paid but the return otherwise could have qualified for that abatement. There were no similar PRN 625/711 penalties in the preceding three periods. The associated Forms 1120 were not late in the preceding three periods.
Keep this limit in view: Do not generalize this procedure to all Form 5472 penalties, all foreign-owned DEs, continuing-failure penalties or other PRNs. The procedure says may be abated; applicable facts and IRS action are still required.
Reasonable cause case by case
Reasonable cause and good faith are evaluated case by case using all relevant facts. Reliance on an accountant, attorney or another professional does not necessarily establish them; that reliance must be reasonable under all the circumstances.[2]
This applies when: The IRS is reviewing reasonable cause and good faith for a section 6038A failure.
Failure penalty
Failure to file Form 5472 at the prescribed time and in the prescribed manner, or to maintain required records, can result in a $25,000 penalty. A substantially incomplete form is treated as a failure to file.[3, p.3]
Cp215 assessment notice
The Form 5472 IRM procedure states that an assessment using MFT 13 and PRN 625 generates and sends a BMF CP 215 penalty notice. This is a post-assessment procedure.[1]
This applies when: This concerns an MFT 13/PRN 625 assessment under IRM 20.1.9.5.2.
Keep this limit in view: Different processing routes may use different PRNs; this does not establish one identical notice code for every Form 5472 case.
Field/section E(4): Address change
Use the applicable item E box when the address changed. This does not replace a separate address-change procedure that is required.[4, p.1] [3, p.2]
Field/section Part II heading: surrogate foreign corporation under section 7874(a)(2)(B)
Check this only when the inversion or surrogate-foreign-corporation rules in the Part II heading apply. It is not a general foreign-shareholder checkbox.[5, p.1] [3, p.4]
Foreign owned us de definition
A foreign-owned U.S. disregarded entity is a domestic disregarded entity wholly owned by a foreign person. Its treatment as a corporation for these purposes is limited to the reporting requirements related to section 6038A.[3, p.2]
Field/section Top annotation: Foreign-owned U.S. DE
Write "Foreign-owned U.S. DE" across the top of the pro forma Form 1120 to identify this special filing.[3, p.2]
Field/section Name: Name
Enter the foreign-owned U.S. DE's name.[4, p.1] [3, p.2]
An illustrative preparation scenario
In this hypothetical preparation example, an owner hears that a first filing problem should qualify for first-time abatement. The preparer gathers the actual penalty and return records and compares them with the procedure's conditions, without describing the owner's situation as eligible merely because it is the first notice they remember. The preparer checks three points: Which penalty and processing route are involved? Does the associated return history meet the specific conditions? Is a limited procedure being generalized beyond its scope? The file remains a working comparison until the relevant facts and applicable instructions have been checked together. No agency outcome is assumed.[1] [2] [3, p.3]
This is a planning illustration, not a statement that a particular filing has been accepted or that an entity qualifies for a tax result. Use the source-backed distinctions above to decide what information still needs to be established before a form is completed.
A review sequence you can actually use
- Which penalty and processing route are involved?
- Does the associated return history meet the specific conditions?
- Is a limited procedure being generalized beyond its scope?
Write down the answer and the record that supports it, rather than marking a question complete because a field contains text. When two records disagree, identify whether the difference concerns the entity, an individual, the reporting period or the type of change. That makes the remaining question specific enough to resolve against the relevant instruction.
Keep the scope of a preparation service separate from the government requirement. A service intake question may gather information for a workflow; it does not create an exception, extend a deadline or determine whether a transaction is reportable. The cited government material remains the basis for those conclusions.
Questions to settle before moving forward
How should I check failure penalty?
Failure to file Form 5472 at the prescribed time and in the prescribed manner, or to maintain required records, can result in a $25,000 penalty. A substantially incomplete form is treated as a failure to file. [3, p.3]
How should I check cp215 assessment notice?
The Form 5472 IRM procedure states that an assessment using MFT 13 and PRN 625 generates and sends a BMF CP 215 penalty notice. This is a post-assessment procedure. This concerns an MFT 13/PRN 625 assessment under IRM 20.1.9.5.2. Different processing routes may use different PRNs; this does not establish one identical notice code for every Form 5472 case.[1]
How should I check field/section e(4): address change?
Use the applicable item E box when the address changed. This does not replace a separate address-change procedure that is required. [4, p.1] [3, p.2]
How should I check field/section part ii heading: surrogate foreign corporation under section 7874(a)(2)(b)?
Check this only when the inversion or surrogate-foreign-corporation rules in the Part II heading apply. It is not a general foreign-shareholder checkbox. [5, p.1] [3, p.4]
Official sources and versions
- Part 20. Penalty and Interest
- 26 CFR 1.6038A-4 Monetary penalty for failure to furnish information or maintain records — 2026-11-05
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- 2025 Form 1120
- Form 5472 (Rev. December 2023) — Rev. December 2023
Get help with the relevant SpeedEIN workflow
SpeedEIN offers preparation and support for the situations described on its service pages. If you would like assistance, review the relevant service scope, supported entities and current availability before ordering. The service does not replace the government’s decision or remove an obligation imposed by the applicable rules.