Foreign, None, N/A or a Reference ID? Missing-Number Instructions Differ by Form
· 6 min read
The answer for this situation
A label that is correct on one IRS form can be wrong when copied into another. This is particularly important when the owner lacks a U.S. identifying number and several forms are being prepared together. Build a form-specific missing-number matrix. Each row should name the form and field, the person or entity identified, the actual number available and the conditions of any alternative entry. The goal is to preserve the meaning of the instructions, rather than making every blank look complete. A number that has not yet been found is also different from a number that the person genuinely does not have.[1, p.3] [2, p.7] [3, p.4]
Which facts change the answer?
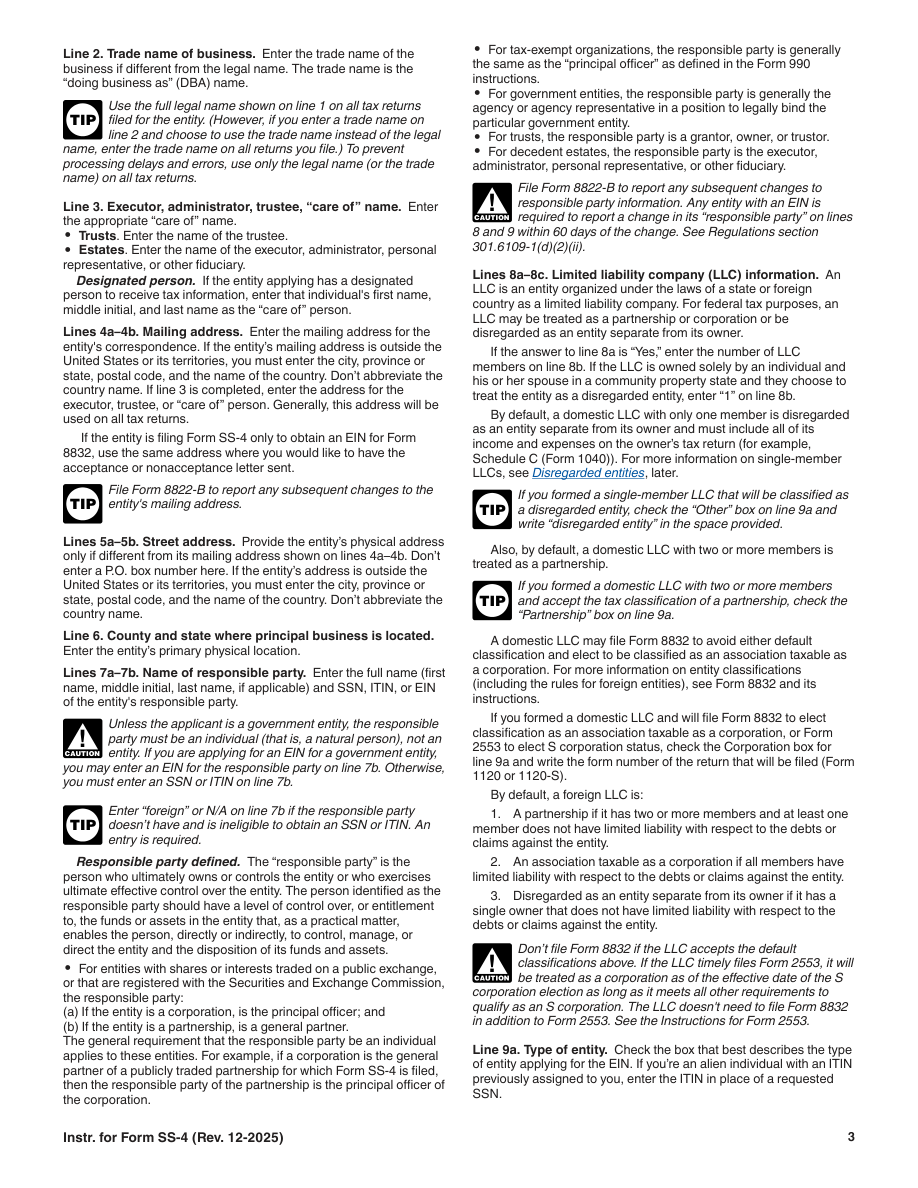
SS-4 line 7b uses foreign or N/A only under the stated condition that the responsible party neither has nor is eligible to obtain an SSN or ITIN. Form 8832's instruction for a foreign owner without a U.S. identifying number is different and should not inherit that additional condition by assumption. Form 5472 separately addresses U.S. identifying numbers, the applicable shareholder reference ID and FTIN entries. The reference ID follows its format and continuity rules; it is not another name for a foreign tax number. These distinctions do not allow an existing required number to be ignored or a general exception to be invented for every unidentified person.[1, p.3] [2, p.7] [3, p.4]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Id exception | Enter foreign or N/A on line 7b only when the responsible party neither has nor is eligible to obtain an SSN or ITIN. The line must contain an entry. | The responsible party does not have an SSN or ITIN. The responsible party is not eligible to obtain an SSN or ITIN. | [1, p.3] |
| Foreign owner without us id | For line 4b, a foreign individual or foreign entity owner without a U.S. identifying number enters none as instructed. This is not a general exception allowing every applicant to omit an identifying number. | — | [2, p.7] |
| Reference id when missing us id | When the applicable foreign shareholder has no U.S. identifying number entered in Part II, use the reference ID required by the instructions. The reporting entity or its representative creates this ID; it is not a separate IRS application. | — | [3, p.4] |
| De ftin none | A foreign-owned U.S. DE reports its direct and ultimate foreign owners' FTINs, if any. If an owner has no FTIN, enter "None" or "N/A" in that field. Different reporting-entity rules must be checked separately. | Foreign-owned U.S. disregarded entity. | [3, p.5] |
| Reference id format | A reference ID may consist of letters only, numbers only, or a combination of letters and numbers, with no spaces or special characters and no more than 50 characters. Keep it consistent for the same person across years, and do not reassign a discontinued ID to another person. | — | [3, p.4] |
| Ein required | Form 8832 requires the entity's own EIN; Applied For is not accepted. An entity that already has an EIN retains that EIN after a classification change. | — | [2, p.7] |
Read the requirements in context
Official field 5472 4b(1): U.S. identifying number, if any
If there is a U.S. identifying number, enter an SSN or ITIN for an individual, or an EIN for another entity.[4, p.1] [3, p.4]
Official field 5472 4b(2): Reference ID number (see instructions)
An applicable foreign shareholder without a U.S. identifying number uses a reference ID: letters, numbers or both, no more than 50 characters, and consistent across years.[4, p.1] [3, p.4]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Imagine a hypothetical owner, Yara, preparing information for an EIN-related review, a supported election and annual reporting. A working note says no U.S. number, so someone suggests writing N/A everywhere. Yara replaces that note with a matrix. The SS-4 row identifies the responsible party and asks about both possession and eligibility under its own exception. The election row identifies the owner and uses the specific foreign-owner instruction only if its facts apply. The Form 5472 section separates the available U.S. number, the applicable reference-ID question and the owner's FTIN. If a number may exist but the document is missing, the row says retrieve record rather than no number. If a reference ID is required, its creation and consistency are treated as that form's task, not as an application for a personal tax number. The same owner can therefore appear in several rows without every field receiving the same text. The example does not decide Yara's eligibility for any particular alternative entry. It shows how to identify the exact condition that must be confirmed before a preparer fills the field, avoiding both invented numbers and an overbroad missing-ID shortcut.[1, p.3] [2, p.7] [3, p.4]
Turn the records into a usable filing plan
Keep the matrix with the source documents and record which facts remain uncertain. Do not treat a foreign identity document, an FTIN, a company EIN and an internally assigned reference ID as interchangeable. Where an existing number is required, find and verify it rather than replacing it with a convenient label. SpeedEIN's supported services should use accurately supplied identification facts within each form's scope, without implying that a general no-SSN marketing description overrides the official conditions. Ask a focused question if the applicable exception is unclear. The final check is whether the prepared entry reflects that form's instruction and the right person, not whether all rows now look alike.[1, p.3] [2, p.7] [3, p.4]
Three checks before you proceed
- Which form and person does this missing-number field concern?
- Have all conditions for the particular alternative entry been checked rather than copied from another form?
- Is the number truly absent, or only missing from the records currently at hand?
Related preparation guides
- Company Documents Show Different Numbers: Map Each IRS Form to the Correct Identifier
- Several IRS Tasks for One LLC: Sequence the Dependencies Before Ordering
- A Foreign Owner Without a U.S. ID: Read the Owner-Identification Exception Carefully
Official sources and document versions
Official source versions checked: 2026-11-10
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Form 5472 (Rev. December 2023) — Rev. December 2023
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.