Several IRS Tasks for One LLC: Sequence the Dependencies Before Ordering
· 5 min read
The answer for this situation
An owner may need an EIN, an address update, an election and annual-filing help in the same broad project. The instinct is to place one order and wait for everything to finish in sequence. Some work depends on a prior fact or identifier, while other records can be organized separately. Build a dependency chart that names the actual tasks and the conditions preventing each one from advancing. This is more useful than assuming the first completed document unlocks every later service. It also prevents a provider's task order from being mistaken for a rule that changes the official deadline or eligibility of another filing.[1] [2, p.7] [3, p.2]
Which facts change the answer?
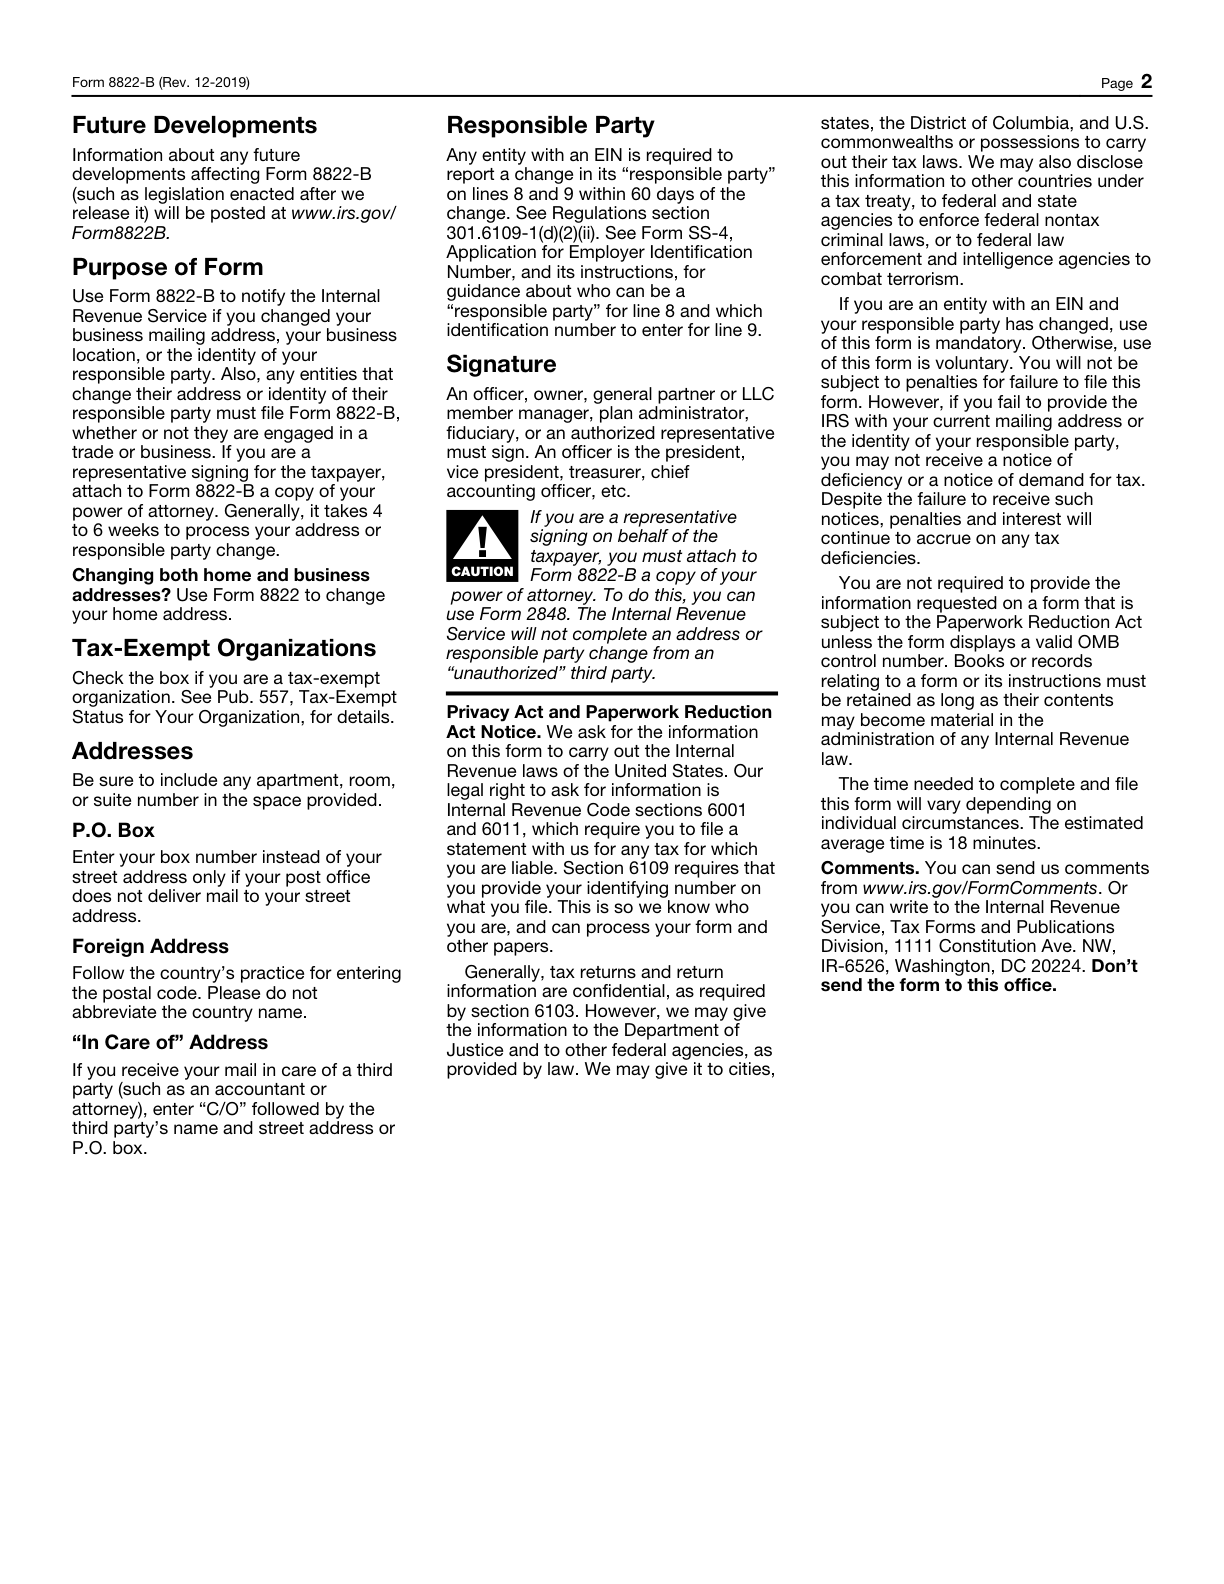
Form 8832 requires the entity's EIN and has its own effective-date and consent rules. Form 8822-B is separately filed and concerns the supported business changes, rather than making every other form an address update. Form 7004 extends only the identified return and follows its applicable original-deadline rule. A foreign-owned U.S. disregarded-entity annual package depends on the actual year, status and reportable transactions. An SS-4 designee's limited authority does not automatically cover every later task. These requirements explain dependencies and separate work; they do not establish a universal filing sequence, a bundled-service promise or a tax-planning recommendation.[1] [2, p.7] [3, p.2]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Form entity before ein | The IRS instructs someone creating a corporation or LLC to form the entity with the state before applying for an EIN. | This does not mean the state filing itself assigns an EIN. | [1] |
| Ein required | Form 8832 requires the entity's own EIN; Applied For is not accepted. An entity that already has an EIN retains that EIN after a classification change. | — | [2, p.7] |
| Purpose | Form 8822-B notifies the IRS of a change to a business mailing address, business location or responsible party. It is not used to change an individual's home address. | — | [3, p.2] |
| Effective window | An ordinary Form 8832 effective date generally cannot precede filing by more than 75 days or follow filing by more than 12 months. Late-election relief is a separate exception requiring its own review. | An ordinary Form 8832 election. Late-election relief for applicants meeting its conditions. | [2, p.6] |
| De proforma required | A foreign-owned U.S. DE subject to Form 5472 filing attaches Form 5472 to a pro forma Form 1120 and files by the Form 1120 due date, including a valid extension. | — | [4, p.2] |
| Separate return | File a separate Form 7004 for each type of return requiring an extension. The extension applies only to the form selected on Part I, line 1. | — | [5, p.1] |
Read the requirements in context
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[4, p.3]
Designee scope
The third-party designee may answer questions about the completed SS-4 and receive the new EIN. Signed authorization is required, and that authority ends when the EIN is assigned and released to the designee.[6, p.6]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Consider a hypothetical owner, Rosa, whose LLC already has an EIN. She plans a mailing-address change, is discussing a possible election with an adviser and also needs to understand the annual reporting work. Instead of writing complete all IRS matters, Rosa lists separate tasks. The identity row confirms the existing EIN evidence. The address row records the old and requested information and the separate update process. The election row waits for the chosen treatment, eligible facts and requested date; it is not started simply to make the project feel comprehensive. The annual row identifies the period and the classification and transaction facts relevant to it. Any extension question is assessed against that specific return's timetable rather than left until the end of the commercial project by default. Rosa can collect transaction records while a different question is being reviewed, but she does not turn incomplete eligibility into an assumed answer. The chart names the next action and decision-maker for each task and shows which items are outside the agreed scope. The result is an understandable work plan, not a guarantee that every item can be handled by one provider or that completing the address row resolves the election and return questions.[1] [2, p.7] [3, p.2]
Turn the records into a usable filing plan
Use the dependency chart when discussing multiple services so that every participant sees the same task boundaries. Distinguish a required prior input from information that can be collected in parallel, and keep official dates separate from internal milestones. Ask SpeedEIN which supported service covers each actual task; do not assume an EIN order includes ongoing comprehensive compliance or that an annual package chooses the owner's tax treatment. When a row is completed, retain its evidence and revisit only the dependencies it actually resolves. This keeps progress concrete while preserving unanswered questions and preventing a convenient project label from replacing the rules for the individual documents.[1] [2, p.7] [3, p.2]
Three checks before you proceed
- What exact input or decision is missing for each separate IRS task?
- Which records can be organized now without assuming unresolved eligibility?
- Are official deadlines and service boundaries still visible apart from the internal project sequence?
Related preparation guides
- An EIN Application, Form 5472 and a W-8 Certificate Go to Different Recipients
- Buying an Existing LLC: Review the IRS Records Before Ordering a Routine Update
- After EIN Assignment: Build Separate Files for IRS Changes and Annual Reporting
Official sources and document versions
Official source versions checked: 2026-11-10
- Get an employer identification number
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Instructions for Form 7004 (Rev. December 2025) — Rev. December 2025
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.