The LLC Pays Its Owner for Work: What Changes in the Preparation File?
· 6 min read
The answer for this situation
A payment described as compensation for an owner's work needs a different factual explanation from money described as owner funding. Start a service-transaction file containing the agreement or description of the work, the invoice where available, the parties involved and the payment trail. The point is to preserve what the payment was said to purchase before choosing a reporting category. Calling every movement an owner contribution can hide a service transaction; calling it a fee does not, by itself, settle withholding, worker status, pricing or personal tax questions. The preparation outcome is a clear account of the claimed service relationship and its unresolved issues, so an ordinary annual-package conversation does not silently expand into specialized tax work.[1, p.2] [2, p.5] [2, p.6]
Which facts change the answer?
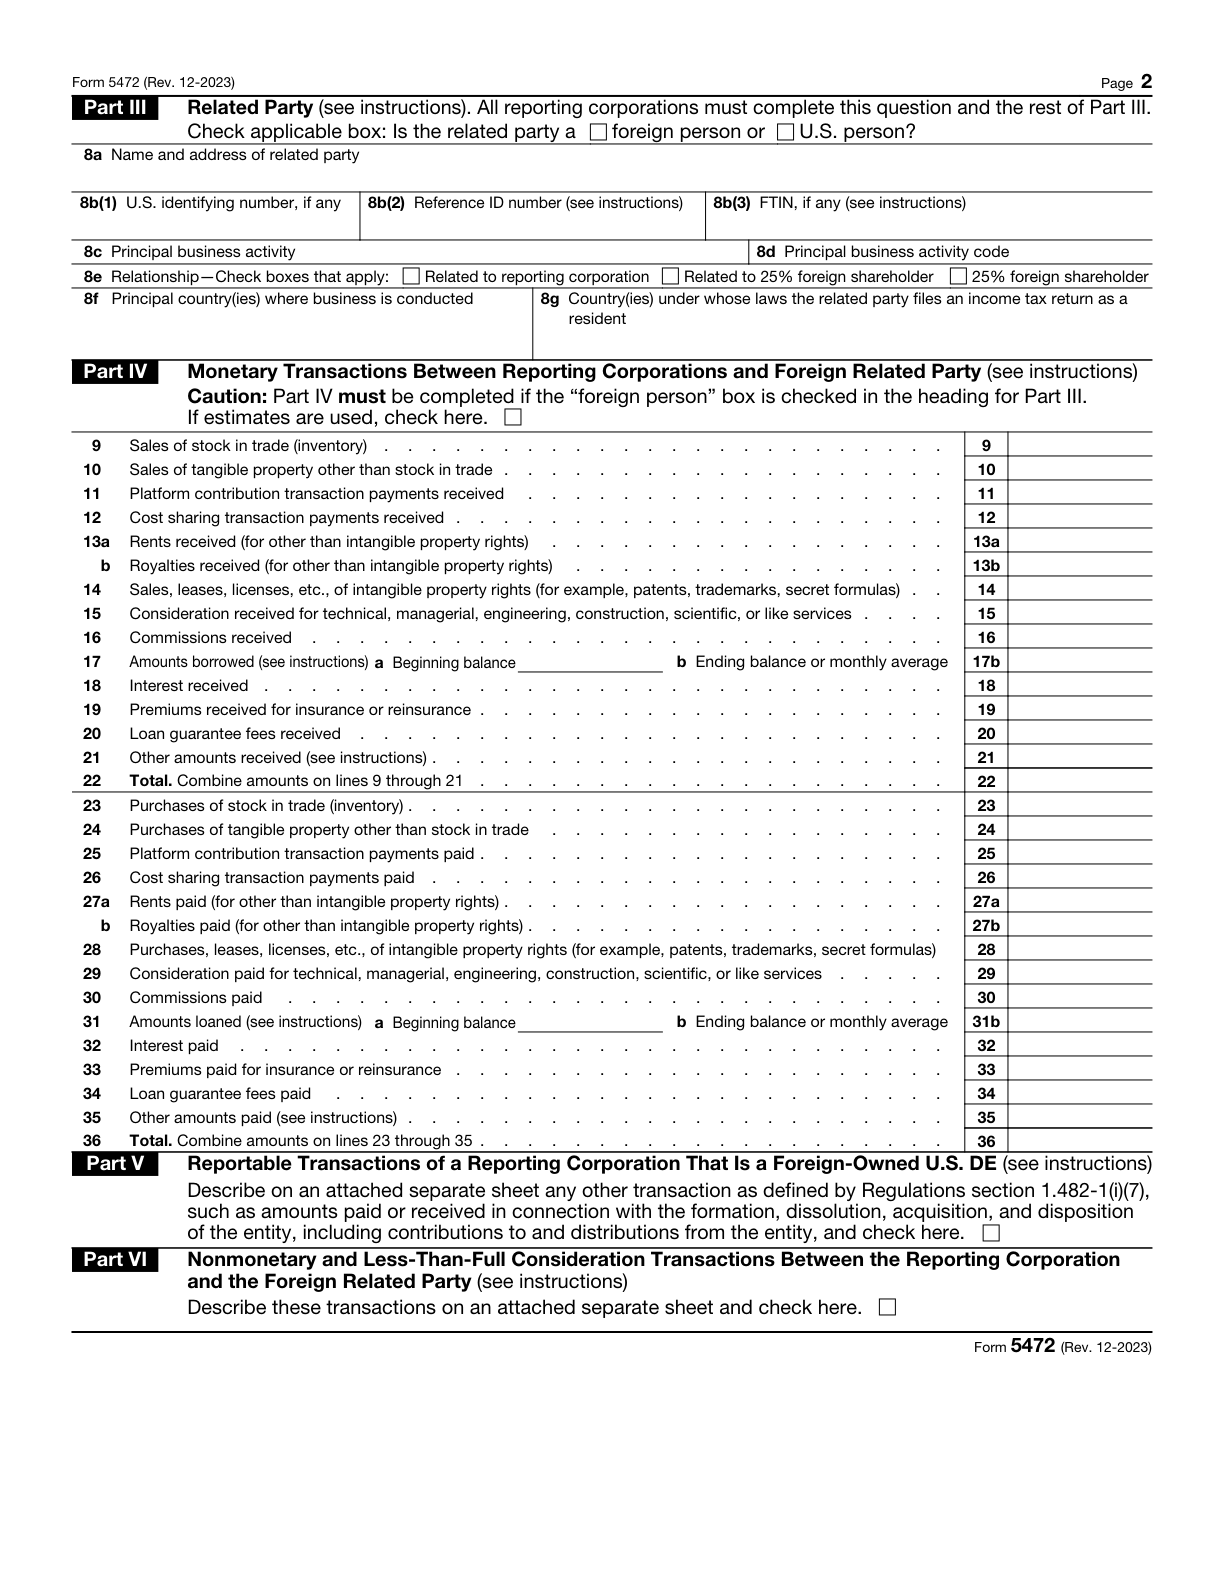
Form 5472 contains separate received and paid categories for the specified technical, managerial, engineering, construction, scientific or like services. The relevant Part IV treatment applies to foreign-related-party transactions, not domestic related parties, and includes applicable accrued receipts or payments where the accrual method applies. For a foreign-owned U.S. DE, Part V addresses other specified transactions not reported in Part IV; it is not a reason to relabel every service payment as capital activity. If a withholding-agent question arises, having no employees does not automatically eliminate the separate date instruction that may apply to payments to nonresident aliens.[1, p.2] [2, p.5] [2, p.6]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Official field 5472 15: Consideration received for technical, managerial, engineering, construction, scientific, or like services | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Consideration received for technical, managerial, engineering, construction, scientific, or like services. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 29: Consideration paid for technical, managerial, engineering, construction, scientific, or like services | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Consideration paid for technical, managerial, engineering, construction, scientific, or like services. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Part5 other de transactions | A foreign-owned U.S. DE checks Part V and attaches a description for other specified transactions not reported in Part IV, including receipts and payments connected with formation, dissolution, acquisition, disposition, contributions and distributions. | Foreign-owned U.S. disregarded entity. The relevant transactions have not been reported in Part IV. | [2, p.6] |
| Records sufficiency | Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3. | — | [2, p.3] |
| Reportable transaction trigger | A reporting corporation generally files Form 5472 when it has a reportable transaction with a foreign or U.S. related party during the tax year. Operating revenue alone does not determine the filing requirement. | — | [2, p.2] |
| Separate related party form | Prepare a separate Form 5472 for each foreign or U.S. related party with which the reporting corporation had reportable transactions. Item 1g is the total number of Forms 5472 for that tax year. | — | [2, p.3] |
Read the requirements in context
Related party repeat part3
Every filer completes Part III, even when that related party was already identified in Part II as a 25% foreign shareholder.[2, p.5]
English usd
Provide Form 5472 information in English and report amounts in U.S. dollars.[1, p.1]
Line1f value
Item 1f is the total U.S.-dollar value of foreign-related-party transactions on that Form 5472, including Part V for a foreign-owned U.S. DE. Do not complete 1f for transactions with a U.S. related party.[2, p.3]
No employees line15
For the ordinary employer branch, line 15 asks for the first date wages or annuities were paid, with N/A entered if no employees are planned. An applicant acting as a withholding agent follows the separate instruction for the date payments to nonresident aliens begin.[3, p.6]
When this applies: The ordinary employer and withholding-agent branches are separate; having no employees does not eliminate an applicable withholding-agent date requirement.
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Suppose an LLC record says that its nonresident individual owner was paid for specified work. The preparer creates a separate service file rather than merging the payment into the contribution schedule. It identifies who performed the work, which party was charged, what the invoice describes and which payment record supports the claimed settlement. A promised fee with no payment is flagged alongside the accounting-method question instead of being dropped merely because the bank statement is quiet. If another transfer is described as returning capital, it remains a different item until its own explanation is supported. The preparer notes any inconsistencies between the agreement, invoice and payment description for clarification. None of this assumes that the stated arrangement is the correct legal characterization. The hypothetical ends with a documented service-transaction question and a list of matters requiring appropriate review. It does not invent a withholding exemption, decide that the owner is an employee or contractor, determine an arm's-length price or conclude that a particular personal return is required. Those additional questions cannot be answered by moving the amount to a simpler-looking spreadsheet column.[1, p.2] [2, p.5] [2, p.6]
Turn the records into a usable filing plan
Use the file to make the preparation scope explicit. Identify the supported transaction description and the form category under consideration, then list any unresolved characterization, accrual, withholding or pricing issue separately. Form 5472 requires English information and U.S.-dollar reporting, with a separate form for each relevant related party with reportable transactions and Part III identification even where that party appears in Part II. Preserve the actual service evidence so the eventual reporting explanation is not based only on a transfer memo. A supported entity type does not guarantee that every transaction it has is within a simplified product's scope. SpeedEIN's standard annual package is for its supported U.S.-formed single-member DE and nonresident-individual-owner facts; it does not imply corporate income-return, personal-tax, transfer-pricing or withholding services. Ask about that boundary using the specific service-transaction file, rather than describing the payment as ordinary funding merely to fit a package. The useful decision is what can be prepared on supported facts and what still needs separate evaluation.[1, p.2] [2, p.5] [2, p.6]
Three checks before you proceed
- Do the agreement, invoice and payment trail describe the same work, parties and amount?
- Have service payments remained distinct from contributions, distributions and other owner movements until their character is supported?
- Are accounting-method, withholding, pricing and service-scope questions clearly identified instead of answered by a convenient label?
Related preparation guides
- Payment-Processor Statements and Form 5472: Separate Sales Receipts From Owner Transfers
- Personal and LLC Transactions Share a Statement: Build a Reviewable Separation Ledger
- A Related-Party Loan Can Move a Filing Beyond a Simplified Cash-Transfer Workflow
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 5472 (Rev. December 2023) — Rev. December 2023
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.