One Client, Several IRS Forms: Build a Signature-and-Authority Matrix
· 5 min read
The answer for this situation
When several IRS tasks are handled together, a client may expect one authorization or signature to cover the entire folder. The forms do not ask the same questions. An SS-4 applicant authorization, a Form 8822-B signature, Form 8832 consent and the no-signature rule for Form 7004 must be kept within their own scope. Build a document-to-authority matrix before collecting approvals. The matrix should identify the task, the person or persons involved and the specific requirement still needing confirmation. It is a coordination aid, not a new form or a way to create authority where the governing instruction does not provide it.[1, p.6] [2, p.2] [3, p.7]
Which facts change the answer?
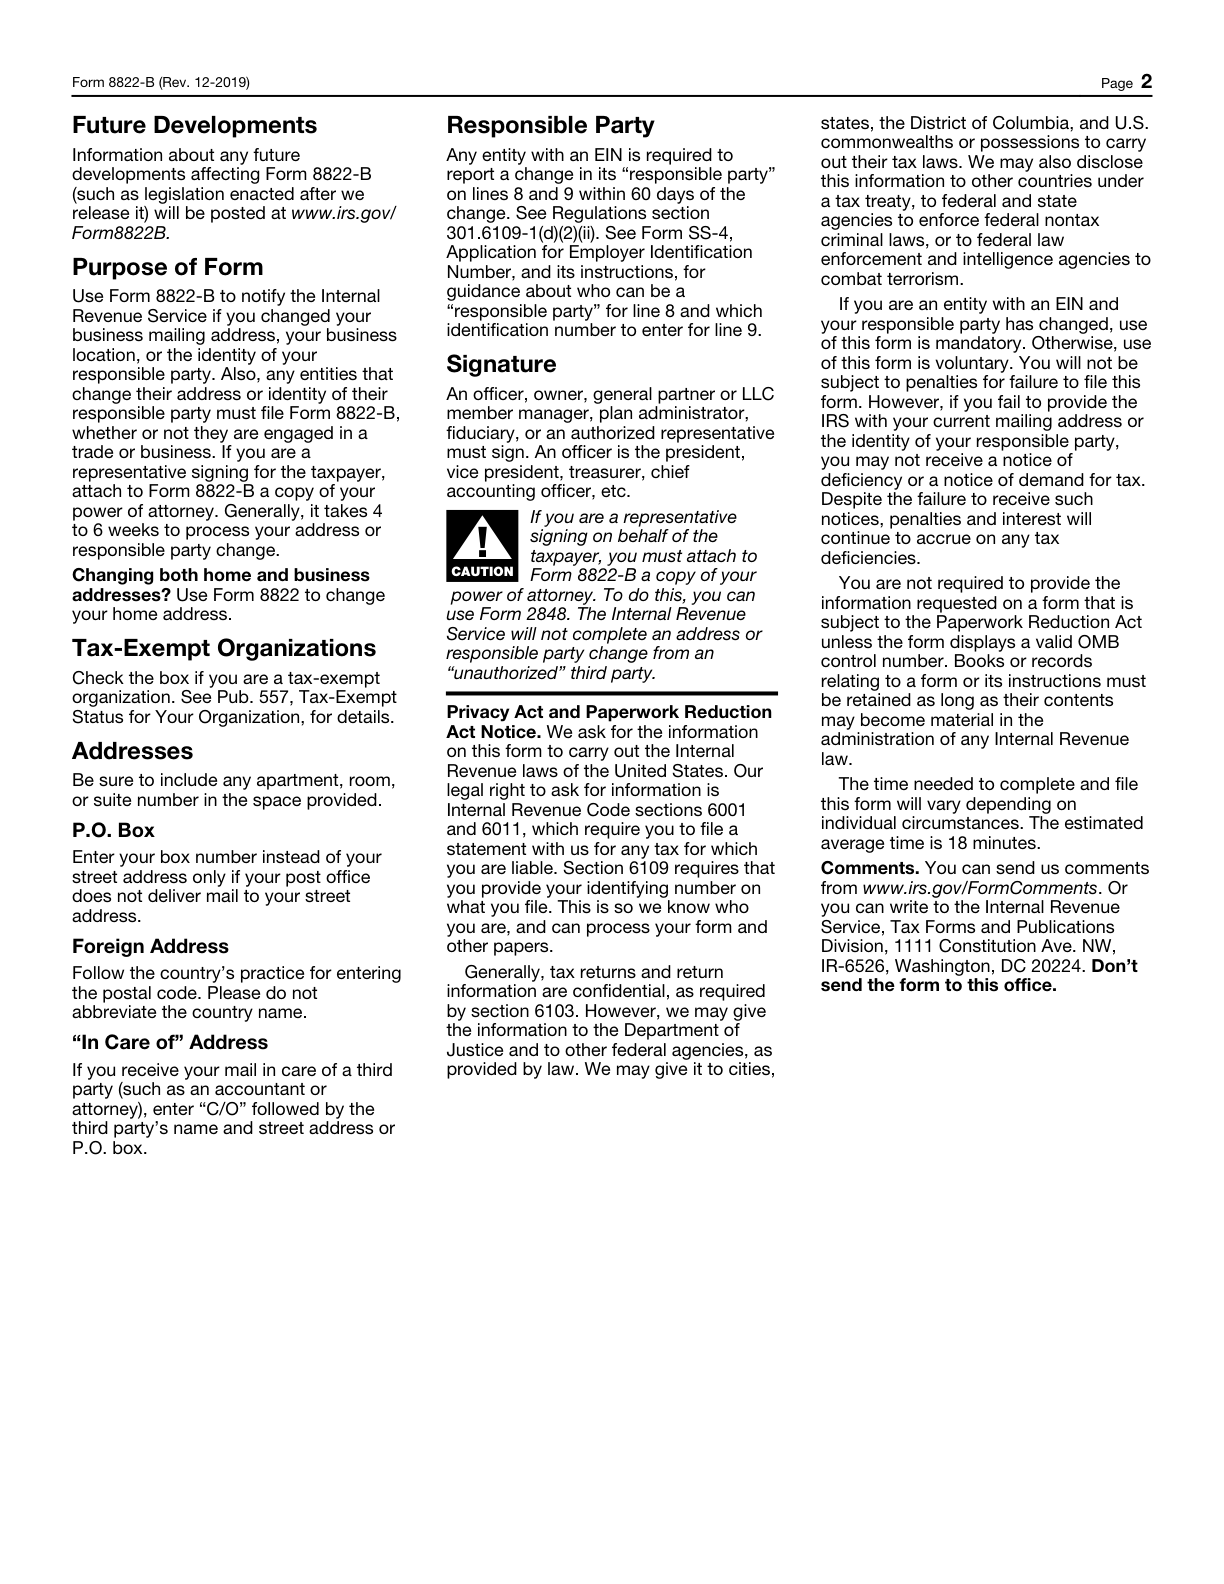
The authorized SS-4 signer depends on the applicant, and a third-party designee has a limited application role. Form 8822-B identifies its applicable signers and requires a representative signing for the taxpayer to attach the relevant power of attorney. Form 8832 has consent and signature requirements, including owner-history conditions where relevant. Its tax-return copy is not signed again under the stated instruction. Form 7004 itself requires no signature. Do not carry these rules into another return or special filing package without checking its own official signature and authority instructions. Electronic-signature permission is also document-specific; one accepted method does not authorize every form or channel.[1, p.6] [2, p.2] [3, p.7]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Authorized signer | The authorized SS-4 signer depends on the type of applicant. A foreign applicant may use a person with appropriate authorization to sign. | — | [1, p.6] |
| Signature authority | Form 8822-B is signed by an owner, officer, general partner, LLC member manager, plan administrator, fiduciary or authorized representative, as applicable. | — | [2, p.2] |
| Consent signatures | Obtain the Form 8832 consent signatures required from applicable members or owners, or an appropriately authorized person. A retroactive effective period can require consent from former owners as well. | — | [3, p.7] |
| No signature | Form 7004 itself does not require a signature. | — | [4, p.1] |
| Designee scope | The third-party designee may answer questions about the completed SS-4 and receive the new EIN. Signed authorization is required, and that authority ends when the EIN is assigned and released to the designee. | — | [1, p.6] |
| Representative poa | A representative signing Form 8822-B for the taxpayer must attach a copy of the power of attorney. An unauthorized third party cannot make the change. | — | [2, p.2] |
Read the requirements in context
Do not sign return copy
The original Form 8832 is signed under the applicable rules. The instructions say not to sign the copy attached to the tax return.[3, p.7]
Document specific permission
IRS electronic-signature permission must be established for the specific document and IRS procedure. A list of acceptable signature technologies is not blanket approval to e-sign every IRS form.[5]
When this applies: IRS guidance permits the signature form and signing process for the specific form or document. The document's identity-verification and other applicable conditions are also met.
Limits to keep: Do not infer IRS acceptance from general e-signature law or a product's signing functionality.
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Consider a hypothetical owner, Priya, coordinating an IRS address update, a supported election and an extension-related task. Her assistant creates one folder called signed forms and asks whether one uploaded signature can finish everything. Priya instead lists each document separately. The address-update row identifies the applicable signer and any representative-authority question. The election row identifies the required consent and the ownership facts relevant to it, not merely the person who is easiest to contact. The extension row preserves the specific no-signature rule rather than adding a signature simply to make all files look alike. The SS-4 history, if used as reference, does not silently grant continuing representation for the later tasks. Priya also distinguishes an original election from a return copy so that the copy instruction is not generalized to the original. For another return or special filing package, the matrix records its own instruction-based signature and authority check instead of borrowing a rule from another row. The resulting file lets the preparer see what has actually been confirmed and what is still open. It does not pronounce every document valid, authorize a particular electronic method or replace a necessary authority review.[1, p.6] [2, p.2] [3, p.7]
Turn the records into a usable filing plan
Use the official document names in the matrix and link each decision to the relevant instruction and confirmed facts. Record who is supplying information separately from who is signing or consenting. If one person performs several roles, keep the legal basis for each role visible rather than treating the shared name as the explanation. SpeedEIN's services remain subject to their individual scopes even when the client has several tasks. Do not market one signature upload as automatic authority for every IRS filing. Resolve document-specific questions before the corresponding step proceeds, and retain the version to which the confirmation relates so that the matrix continues to describe the actual work.[1, p.6] [2, p.2] [3, p.7]
Three checks before you proceed
- Does every document have its own signer, consent or no-signature analysis?
- Has authority been distinguished from being a contact or supplying information?
- Have other returns and special filing packages been checked on their own terms, including any applicable electronic-signature permission?
Related preparation guides
- The Data Changed After Approval: Keep the Signed Version and Revised Instructions Aligned
- Owner, Manager, Organizer and Agent: Match Each Person to the IRS Task
- Preparing an SS-4 for Someone Else: Authorized Signature and Designee Are Different
Official sources and document versions
Official source versions checked: 2026-11-10
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Form 8822-B (Rev. December 2019) — Rev. December 2019
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form 7004 (Rev. December 2025) — Rev. December 2025
- Part 10. Security, Privacy, Assurance and Artificial Intelligence
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.