The Form Was Prepared Weeks Ago: Recheck the Source Version Before Submission
· 6 min read
The answer for this situation
A packet prepared several weeks earlier can contain correct data and still deserve a final check of the source it relies on. The issue is not to chase every new date online or replace every older form. It is to confirm that the actual document, period and submission route still match the applicable official instructions. Build a final version-comparison sheet with the source used for preparation and the currently checked official material. Record whether a difference is a meaningful instruction change, a different annual form or merely a date that does not establish applicability on its own. That gives the preparer a concrete issue to assess before sending.[1, p.1] [2, p.3] [2, p.2] [3, p.1] [4] [5]
Which facts change the answer?
An annual Form 1120 version and a continuously revised form must be matched to their different year and revision meanings. Form 8832's current address overlay supersedes the corresponding older addresses in the same document. A foreign-owned U.S. disregarded entity follows its special submission route, and private-delivery rules apply only to designated products under their conditions. These are examples of why the source must be read in context. Do not assume a newer download automatically applies to every earlier tax year, or that a carrier name proves a particular service qualifies. This guide does not create an effective-date rule for an unexamined change.[1, p.1] [2, p.3] [2, p.2] [3, p.1] [4] [5]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Address overlay controls | The updated address sheet at the beginning of the current Form 8832 PDF supersedes the corresponding older addresses in its instructions. Do not continue using an outdated address table from later pages. | — | [1, p.1] |
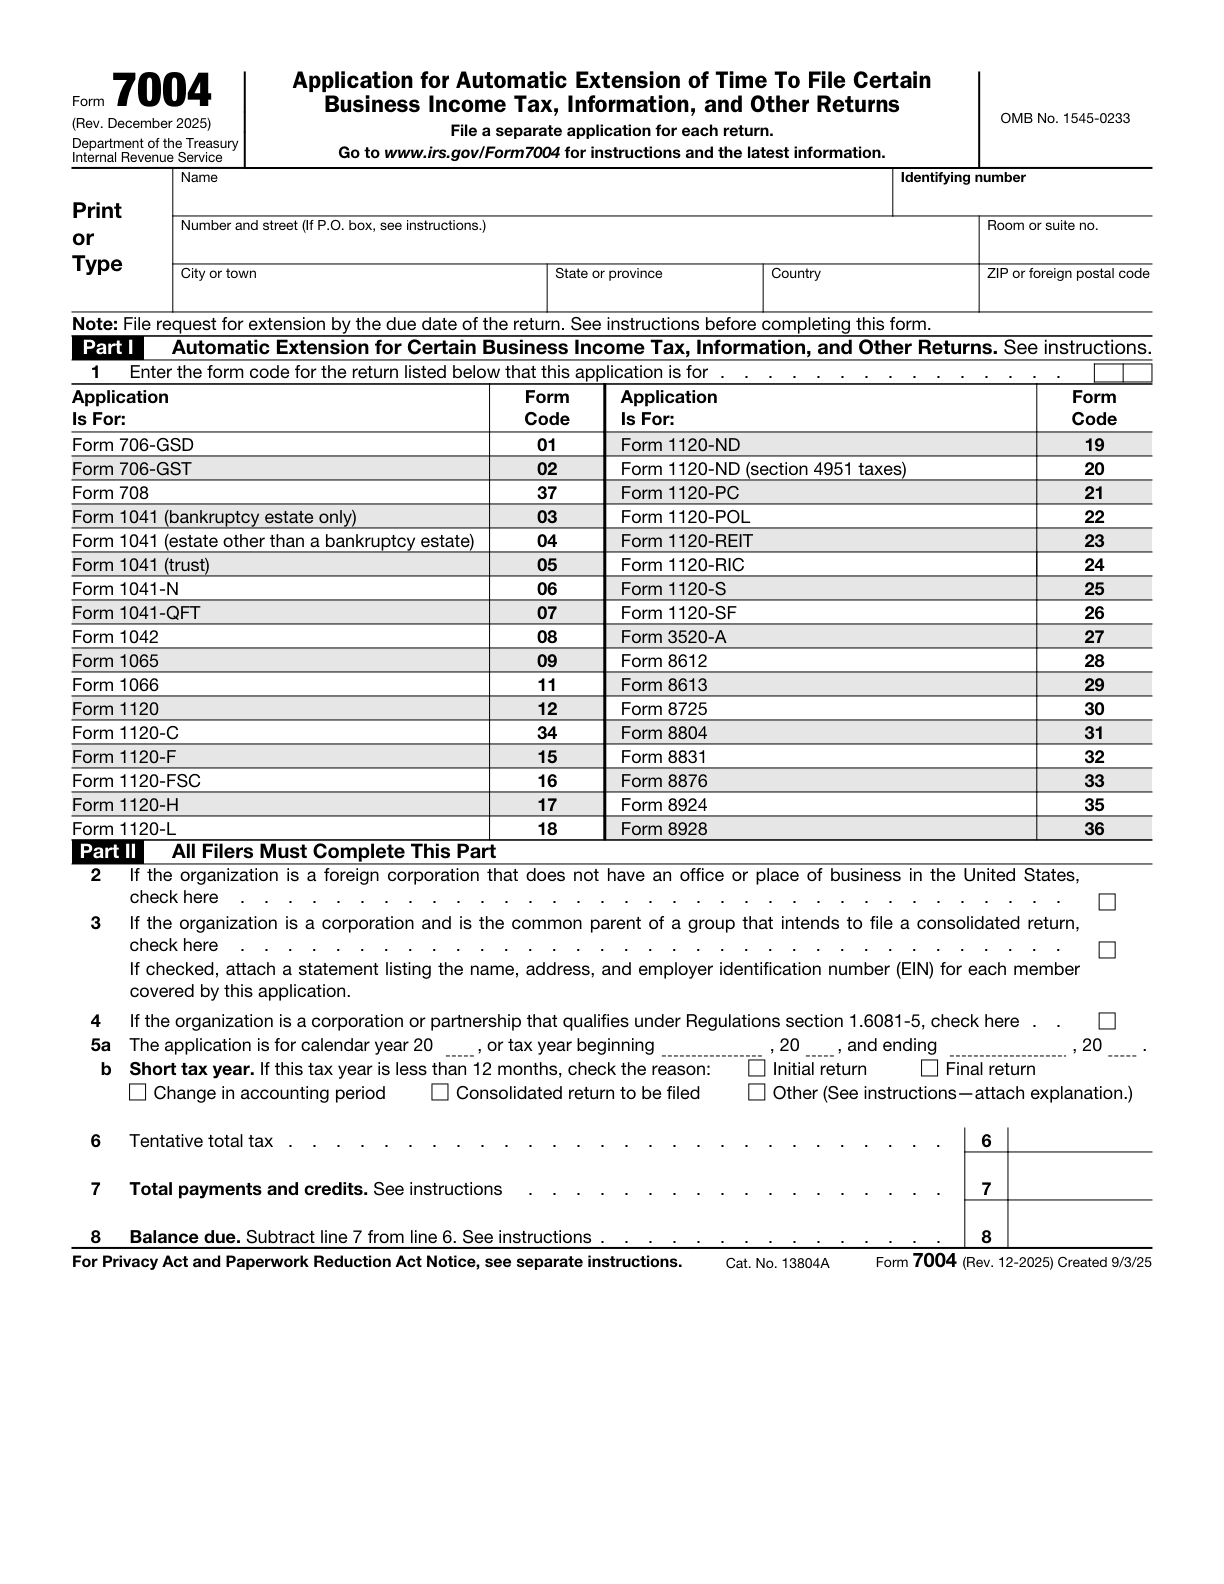
| Foreign owned de special route | A foreign-owned U.S. disregarded entity extending its Form 5472/pro forma 1120 package uses the Form 1120 code on line 1, writes Foreign-owned U.S. DE across the top and follows the special fax or mailing route in the Form 5472 instructions, rather than ordinary Form 7004 addresses. | The filer is a foreign-owned U.S. disregarded entity. The extension concerns its Form 5472/pro forma 1120 package. | [2, p.3] [2, p.2] [3, p.1] |
| Designated product only | The PDS timely-mailing rule applies only to the specific delivery products designated by the IRS. A DHL, FedEx or UPS brand name alone does not make all of that carrier's services eligible. | A private carrier is used to claim the section 7502 designated-delivery-service rule. The actual delivery product is on the IRS designated list applicable at the time. Check the designated-product list and delivery address when sending the filing. This fact concerns mailing or designated PDS rules. It does not establish that an ordinary fax transmission time or fax receipt satisfies section 7502. | [4] [5] |
| De tax year | A foreign-owned U.S. DE uses the tax year its owner uses for U.S. tax filing. If the owner does not have such a tax year, the DE uses a calendar year. | — | [2, p.2] |
| De mail route | A foreign-owned U.S. DE uses the special PIN Unit mailing route in the Form 5472 instructions, rather than the ordinary Form 1120 mailing addresses. | Applies to the Form 5472/pro forma Form 1120 package for a foreign-owned U.S. DE. | [2, p.2] |
| De fax route | For the foreign-owned U.S. DE filing package, the Form 5472 instructions permit faxing to 855-887-7737 at 300 DPI or higher, or using the special mailing address in those instructions. | Applies to the Form 5472/pro forma Form 1120 package for a foreign-owned U.S. DE. | [2, p.2] |
Read the requirements in context
Form1120 year 2024
The official 2024 Form 1120 identifies calendar year 2024 or a tax year beginning in 2024.[6, p.1]
When this applies: Annual Form 1120 tax year only; continuous Form 5472 revision applicability must be checked separately.
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[2, p.3]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Imagine a hypothetical owner, Jules, whose preparation file has a completed draft, a source PDF saved earlier and a mailing plan. Before submission, the reviewer compares the actual forms and period with the current official instructions relevant to that task. One question concerns an address update sheet; another concerns whether an annual form version matches the reporting year. Jules does not replace every file simply because a webpage has a newer retrieval date. The comparison identifies the exact passage or field that matters, the previous assumption and the action needing confirmation. If a mailing plan refers only to a delivery company's brand, the reviewer checks the actual product and applicable route instead of assuming all services qualify. Where the source difference is not understood, the issue remains open rather than being resolved by picking the newest-looking attachment. The intended submission version is then linked to the instruction check and any resulting approved correction. This example does not claim that a change always affects Jules's filing or prescribe a universal way to fix an already sent packet. It demonstrates a controlled final review that preserves the distinction between current source availability, applicable tax year and actual submission requirements.[1, p.1] [2, p.3] [2, p.2] [3, p.1] [4] [5]
Turn the records into a usable filing plan
Keep the comparison short enough to explain what was checked and why it matters. The owner should be able to see the actual issue, not an unexplained demand to redo the whole file. A document-specific correction should be assessed for any related content or authorization question under its own instructions. SpeedEIN's supported preparation and submission assistance should use the applicable official material without promising that a saved draft is permanently current. Do not turn the comparison into a claim that every internal note is an IRS-required attachment. Retain the final checked version and describe the work accurately, while leaving substantive applicability questions to the relevant official context and appropriate review.[1, p.1] [2, p.3] [2, p.2] [3, p.1] [4] [5]
Three checks before you proceed
- Does the actual form version fit the reporting period and stated procedure?
- Has a meaningful source difference been identified rather than inferred from a newer date alone?
- Does the submission plan match the official route and, where relevant, the specific designated delivery product?
Related preparation guides
- A Fax Failed Near the Filing Deadline: Preserve the Error and Plan the Next Step
- Mailing From Abroad: Do Not Confuse an Overseas Postmark With the U.S. Mailing Rule
- The Current Form 8832 Address Overlay Controls the Mailing Route
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Form 7004 (Rev. December 2025) — Rev. December 2025
- Private delivery services (PDS)
- 26 U.S.C. § 7502: Timely mailing treated as timely filing and paying
- 2024 Form 1120
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.