A Federal Tax Election and a State Entity Conversion Are Different Projects
· 5 min read
The answer for this situation
An owner saying I want the LLC to become a corporation may be describing a tax preference, a legal-entity project or both. A preparer cannot safely resolve the ambiguity by sending the same document for every meaning. Start with a two-project map. One side describes the existing entity and the federal treatment being requested. The other records whether the owner is actually asking for a change under the relevant state's law. Keep the intended outcome written in ordinary language before selecting a service. This makes it possible to discuss a supported election without implying that a federal form performs every state filing the owner might have in mind.[1, p.5] [1, p.3]
Which facts change the answer?
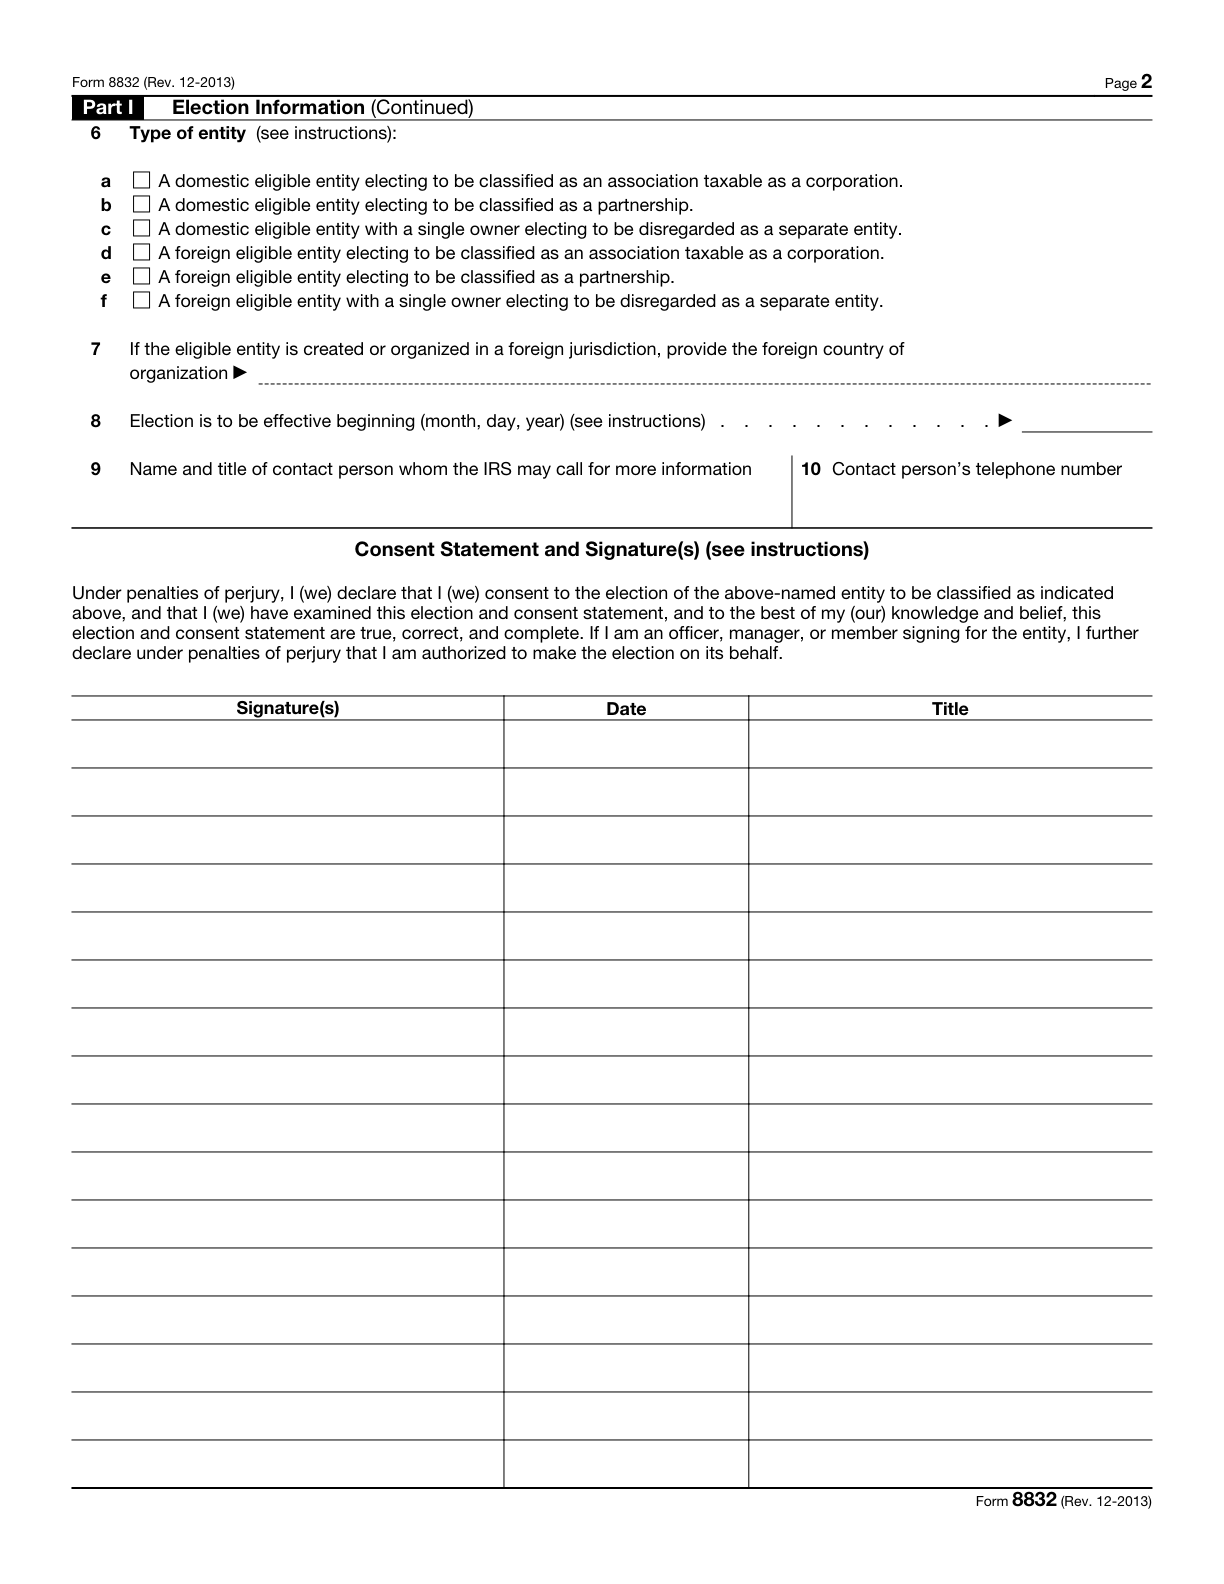
Form 8832 distinguishes the federal classifications available to eligible entities and the conditions for making the election. An SS-4 entity-type answer is not that election. The state entity's formation and filed records have their own rules and sources. Wyoming's provisions, for example, describe an LLC as an entity distinct from its members; that state-specific source should not be converted into a nationwide conversion procedure. This article does not choose a legal restructuring route or calculate its tax effects. SpeedEIN's standard election service concerns the stated U.S. single-individual-owner LLC and an already chosen treatment, not a comprehensive state conversion or corporate-tax planning engagement.[1, p.5] [1, p.3]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Domestic default | Without an election, a domestic eligible entity with two or more members generally defaults to a partnership; one with a single owner generally defaults to a disregarded entity. | — | [1, p.5] |
| Official field 8832 6a: A domestic eligible entity electing to be classified as an association taxable as a corporation. | Use this item when a domestic eligible entity elects taxation as a corporation. | — | [1, p.3] |
| Official field 8832 6c: A domestic eligible entity with a single owner electing to be disregarded as a separate entity. | Use this item when a domestic eligible entity with one owner elects disregarded status. First check the default rules and classification-change limits. | — | [1, p.3] |
| Not entity election | Checking an entity-type box on SS-4 is not itself an entity-classification tax election. | — | [2, p.4] |
| Return copy | In addition to filing Form 8832 separately, attach a copy to the entity's return for the election year as instructed, or to the applicable direct or indirect owner's return if the entity has no return-filing obligation. | — | [1, p.6] |
| Foreign owned us de definition | A foreign-owned U.S. disregarded entity is a domestic disregarded entity wholly owned by a foreign person. Its treatment as a corporation for these purposes is limited to the reporting requirements related to section 6038A. | — | [3, p.2] |
Read the requirements in context
Separate entity
Wyoming law describes an LLC as an entity distinct from its members and gives it perpetual duration.[4, p.677]
When this applies: This does not eliminate dissolution, winding-up, licensing or tax obligations.
Form entity before ein
The IRS instructs someone creating a corporation or LLC to form the entity with the state before applying for an EIN.[5]
When this applies: This does not mean the state filing itself assigns an EIN.
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Imagine a hypothetical Wyoming LLC owned by Clara. Her adviser has discussed corporate taxation, and Clara writes convert company on the project request. Before anyone fills out a form, they separate what the words mean. The existing formation record identifies the LLC. The adviser's instruction identifies the tax treatment Clara wants considered. A third note asks whether she also wants the state-law entity or state-filed records changed. That third question is not silently marked complete when the federal election is prepared. Clara's project map names the relevant agency, proposed document, required decision and evidence of completion for each task. If she wants a state change, the applicable Wyoming materials must be reviewed for that particular project; a general statement about federal classification is not substituted for them. If the intention is only the supported federal election, the scope remains clear without suggesting that every company record will now be rewritten. Clara also keeps the EIN identity and any later return questions as related records, rather than assuming that a new word in the service conversation settles them. The result is a clarified instruction that the preparer can act on, not a claim that either possible project is automatically appropriate or complete.[1, p.5] [1, p.3]
Turn the records into a usable filing plan
Before ordering, ask what document will be prepared, what authority receives it and what outcome the service actually covers. Compare that answer with the owner's intended result. Keep state-law questions with their applicable jurisdictional sources and federal-election questions with the governing IRS instructions. Do not infer a new EIN requirement or a full corporate-return engagement solely from the casual phrase become a corporation. SpeedEIN can assist with its supported standard election after eligibility and the desired treatment have been established. If the project also includes restructuring or other filings, assign those separately rather than using a single confirmation message to imply they have all been handled.[1, p.5] [1, p.3]
Three checks before you proceed
- Does the request concern federal treatment, a state-law entity change or two separate projects?
- Which agency, document and applicable source support each proposed action?
- Does the chosen service actually cover the intended outcome rather than only one part of it?
Related preparation guides
- Changing Tax Classification While Keeping the EIN: Avoid Buying the Wrong Application
- Track a Form 8832 Decision From Mailing Evidence to the IRS Letter
- A Classification Election Can Change the Return You Need to Prepare
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form SS-4 (Rev. December 2025) — Rev. December 2025
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
- Wyoming Title 17 corporations partnerships and associations
- Get an employer identification number
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.