Track a Form 8832 Decision From Mailing Evidence to the IRS Letter
· 5 min read
The answer for this situation
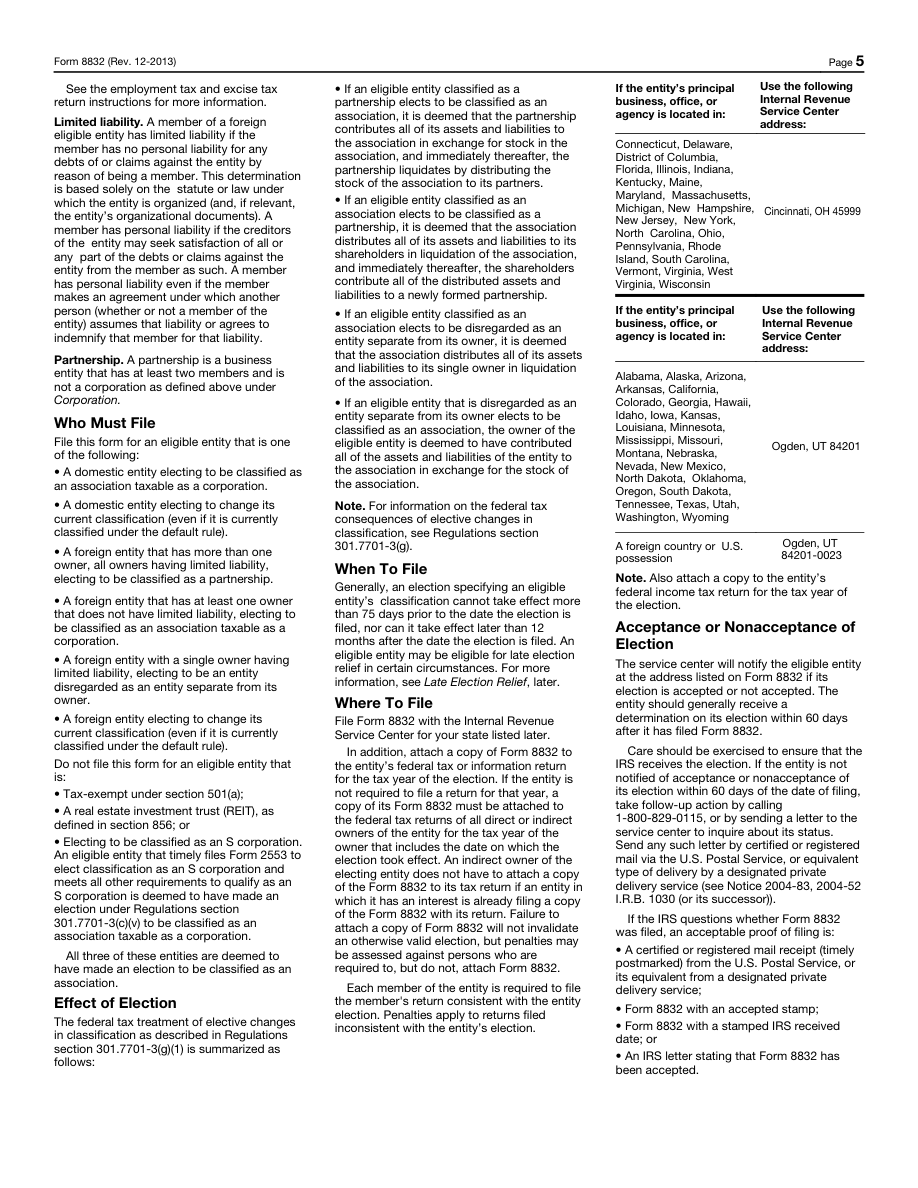
A prepared election, an envelope sent to the IRS and a letter about that election answer different questions. If the project status is simply complete, an owner may not know which event actually occurred. Create a decision log that starts with what was requested and then records what the available evidence establishes. The log should let a later reviewer compare the submitted form with the actual IRS communication, rather than reconstructing the story from a payment receipt or a message saying mailed. This is an organizational method for a supported election, not a promise that the IRS will decide it by a particular date.[1, p.6] [1, p.7]
Which facts change the answer?
Form 8832 has its own effective-date, eligibility and consent rules. Its separately filed election and the copy attached to an applicable return serve different steps. Proof of mailing does not itself state an accepted classification or effective date. Likewise, keeping a return copy does not establish that an earlier election was accepted. Read actual IRS correspondence for what it says, and keep a request for information, a decision and an unresolved discrepancy clearly distinguished. Do not infer a result from the fact that the company has an EIN. The standard preparation service does not decide tax consequences or turn a requested date into a guaranteed effective date.[1, p.6] [1, p.7]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Effective window | An ordinary Form 8832 effective date generally cannot precede filing by more than 75 days or follow filing by more than 12 months. Late-election relief is a separate exception requiring its own review. | An ordinary Form 8832 election. Late-election relief for applicants meeting its conditions. | [1, p.6] |
| Return copy | In addition to filing Form 8832 separately, attach a copy to the entity's return for the election year as instructed, or to the applicable direct or indirect owner's return if the entity has no return-filing obligation. | — | [1, p.6] |
| Consent signatures | Obtain the Form 8832 consent signatures required from applicable members or owners, or an appropriately authorized person. A retroactive effective period can require consent from former owners as well. | — | [1, p.7] |
| Address overlay controls | The updated address sheet at the beginning of the current Form 8832 PDF supersedes the corresponding older addresses in its instructions. Do not continue using an outdated address table from later pages. | — | [1, p.1] |
| Ein required | Form 8832 requires the entity's own EIN; Applied For is not accepted. An entity that already has an EIN retains that EIN after a classification change. | — | [1, p.7] |
| Official field 8832 9: Name and title of contact person whom the IRS may call for more information | Enter the name and title of the person the IRS may contact about this election. | — | [1, p.3] |
Read the requirements in context
Official field 8832 10: Contact person’s telephone number
Enter the telephone number of the contact on line 9.[1, p.3]
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[2, p.3]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Consider a hypothetical owner, Marco, who asked for a standard election after discussing his intended treatment with an adviser. The company folder contains a signed draft, a later prepared version and mailing evidence. Months later another preparer asks what treatment is in effect. Marco should not forward whichever PDF appears first in the folder. He builds a log with separate entries for the approved request, the as-submitted version, the destination and the evidence of sending. When an IRS letter is available, he records its date, the company identity it concerns and the classification or effective-date information it actually states. He compares those details with the submitted request rather than assuming the original working draft is authoritative. If the letter raises a question or contains a detail that needs review, the log keeps that issue open and identifies who is handling it. Marco does not respond to uncertainty by automatically submitting another election. He supplies the actual documents to the person qualified to assess the discrepancy and the applicable next step. The result is a readable account of the project, useful when preparing a later return or reviewing service eligibility. The example is not an IRS acceptance story or a procedure for correcting every type of election problem.[1, p.6] [1, p.7]
Turn the records into a usable filing plan
Use precise status descriptions such as approved for submission, sent under the stated route, correspondence received and discrepancy under review. Each status should point to its supporting document. Keep the original request and the actual response so that future work can distinguish requested treatment from confirmed information. If SpeedEIN is handling a supported election, share later correspondence within the agreed project instead of summarizing it from memory. Do not promise that a generic approval notice or a particular processing period applies without checking the relevant source and facts. Where the outcome affects a later annual package, resolve the classification question before treating the company as eligible for that separate service.[1, p.6] [1, p.7]
Three checks before you proceed
- Which version was actually submitted, and which document supports that event?
- What does the IRS correspondence actually state about the entity and requested election?
- Is any difference still open for review before a later return or service eligibility decision?
Related preparation guides
- The Form 8832 Contact Person and the Consenting Owner Have Different Roles
- Returning to Disregarded Treatment: Prepare the Prior-Election and Adviser File First
- Build a Form 8832 Decision File: EIN, Ownership, Dates, and Intended Classification
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 8832 (Rev. December 2013) — Rev. December 2013
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.