Related-Party Contracts or Capital Funding? Sort Operational Payments Before Preparation
· 6 min read
The answer for this situation
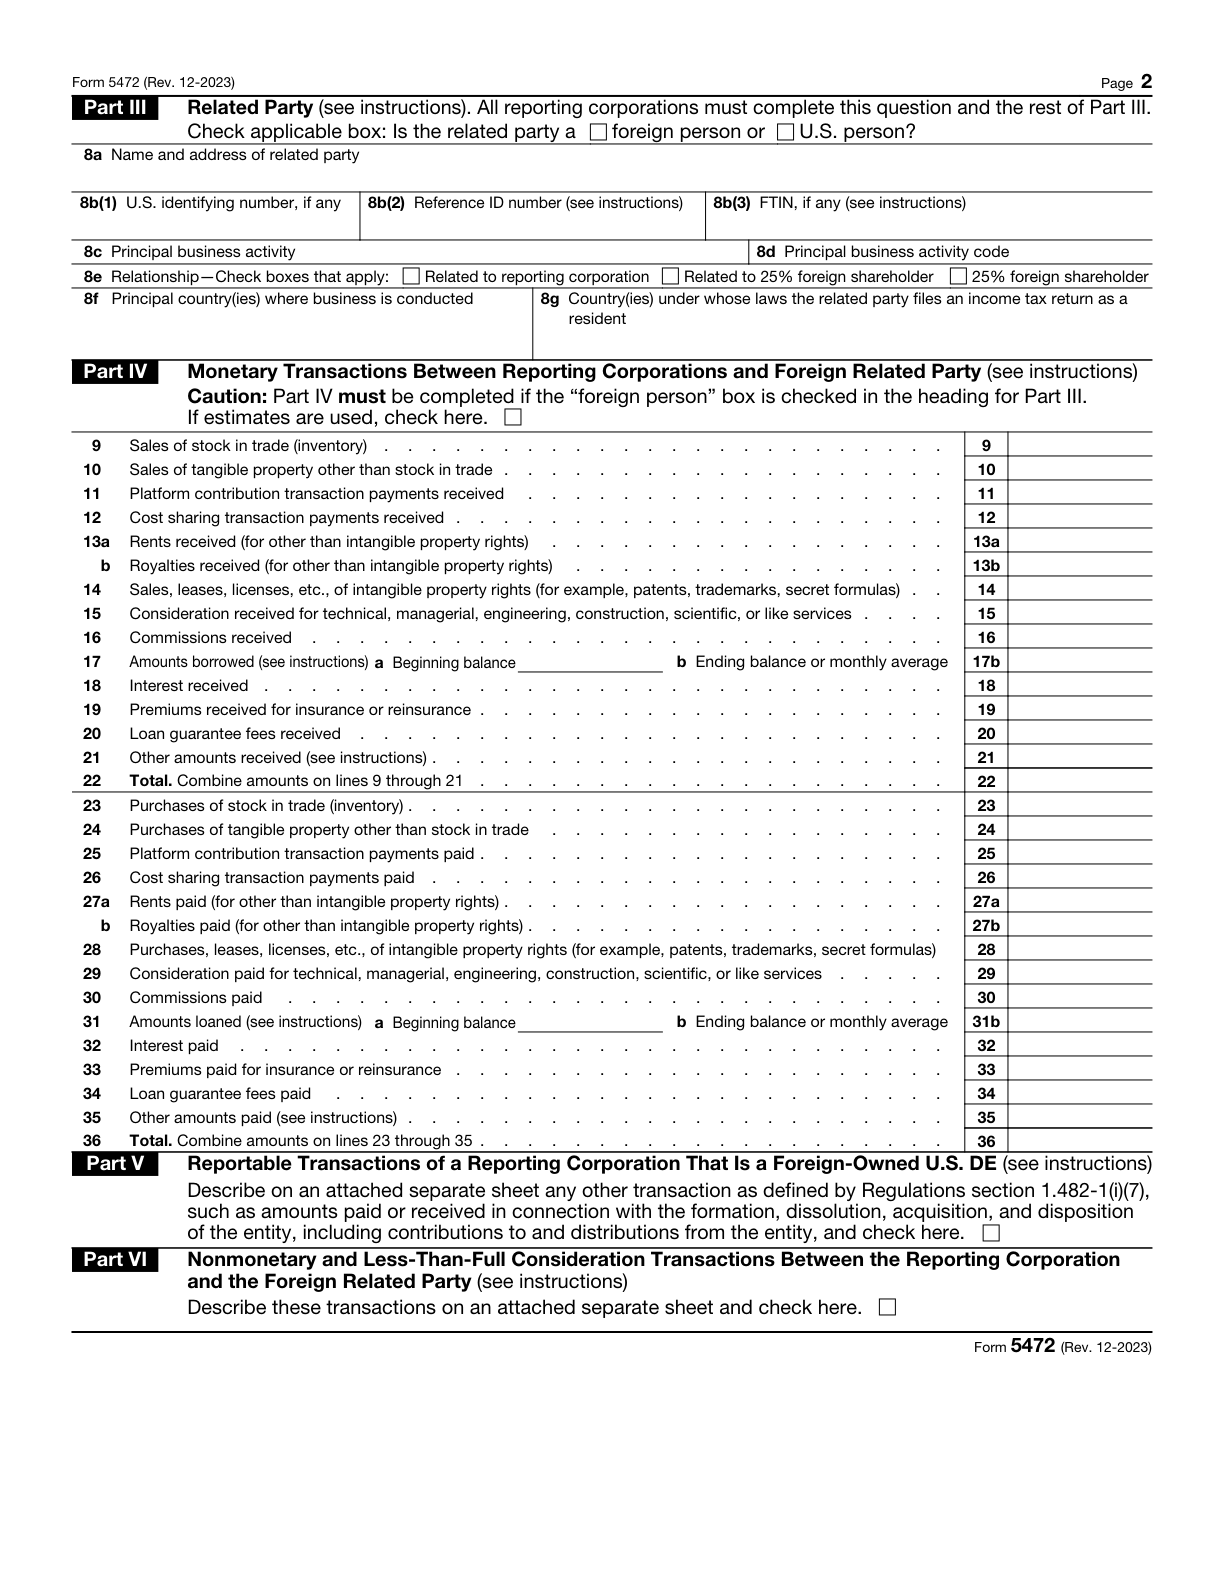
Sort a related-party payment by its documented purpose before treating every owner-connected transfer as capital funding. Contracts, invoices and accounting descriptions may point to very different arrangements: an operational service, use of property or rights, or a movement connected with funding the entity. A practical preparation matrix can place those descriptions beside the actual parties and the direction of the receipt or payment. Its purpose is to identify the question that needs answering, not to declare that the transaction has already been classified correctly. The selected official fields distinguish several categories and include conditions that a bank-only summary can overlook. A matrix that preserves those distinctions is more useful than one broad total called support from owner, especially where the actual arrangement may exceed a standard annual service's scope.[1, p.2] [2, p.5]
Which facts change the answer?
The cited Part IV categories relate to foreign related parties, with accrued receipts or payments included where the accrual method applies. Do not extend those directions automatically to domestic-related-party transactions or assume that every relevant amount appears as a bank transfer in the period. The separate Part V rule for specified DE transactions retains its own conditions, including whether the transactions were already reported in Part IV. This article does not determine arm's-length pricing, withholding, intellectual-property treatment or the legal character of a funding arrangement. Those questions require the facts and, where necessary, appropriate specialist review.[1, p.2] [2, p.5]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
| Official field 5472 13a: Rents received (for other than intangible property rights) | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Rents received (for other than intangible property rights). Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 14: Sales, leases, licenses, etc., of intangible property rights | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Sales, leases, licenses, etc., of intangible property rights. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 15: Consideration received for technical, managerial, engineering, construction, scientific, or like services | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Consideration received for technical, managerial, engineering, construction, scientific, or like services. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 27a: Rents paid (for other than intangible property rights) | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Rents paid (for other than intangible property rights). Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 28: Purchases, leases, licenses, etc., of intangible property rights | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Purchases, leases, licenses, etc., of intangible property rights. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
| Official field 5472 29: Consideration paid for technical, managerial, engineering, construction, scientific, or like services | If this foreign-related-party transaction occurred, report its U.S.-dollar amount under Consideration paid for technical, managerial, engineering, construction, scientific, or like services. Include accrued receipts or payments where the accrual method applies. | Part IV concerns transactions with foreign related parties, not domestic related parties. | [1, p.2] [2, p.5] |
Read the requirements in context
Part5 other de transactions
A foreign-owned U.S. DE checks Part V and attaches a description for other specified transactions not reported in Part IV, including receipts and payments connected with formation, dissolution, acquisition, disposition, contributions and distributions.[2, p.6]
When this applies: Foreign-owned U.S. disregarded entity. The relevant transactions have not been reported in Part IV.
Records sufficiency
Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3.[2, p.3]
Reportable transaction trigger
A reporting corporation generally files Form 5472 when it has a reportable transaction with a foreign or U.S. related party during the tax year. Operating revenue alone does not determine the filing requirement.[2, p.2]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Suppose a hypothetical LLC's owner provides funds, while a separate agreement describes administrative services and another document concerns access to software rights. The accounting export calls all three owner support. A preparer records the stated purpose, the named counterparty and the available agreement or invoice for each item. The preparer does not immediately assign every row to a contribution category, nor copy one contract description across the whole ledger. A payment that seems connected with services receives a focused question about what was actually supplied and by whom. A rights-related item stays separate from an ordinary property-rent description. If the accounting method makes accrual information relevant, the preparer requests clarification of the corresponding records rather than assuming the bank export is complete. The funding movement is considered on its own facts and with the applicable Part V conditions in view. A conflict between the contract and the transfer description is labelled for resolution before the worksheet is treated as final. This hypothetical matrix makes the operational and funding questions visible; it does not establish a price, settle a specialist tax issue or promise that every listed arrangement will be accepted within an ordinary annual package.[1, p.2] [2, p.5]
Turn the records into a usable filing plan
When reviewing the matrix, ask whether each description identifies the actual arrangement rather than merely repeating the account name. Keep receipts and payments distinguishable, and retain references that explain the preparation question without describing every listed business document as an IRS-mandated attachment. A row can remain unresolved while the owner obtains a clearer factual explanation. That is preferable to choosing the nearest-looking category solely to make the schedule complete. Where an arrangement involves services, rights, rent or other specialist considerations, disclose it before selecting a preparation service. SpeedEIN's normal annual scope should not be treated as an offer to analyze transfer pricing, withholding or every operational contract. The matrix can support a scope discussion and a targeted request for information, while the official instructions and the established facts remain the basis for any eventual reporting treatment.[1, p.2] [2, p.5]
Three checks before you proceed
- Does each receipt or payment have an identified counterparty, direction and supported purpose beyond its accounting label?
- Have the foreign-related-party and accounting-method conditions been retained when considering the relevant fields?
- Which operational or funding arrangements require further facts or specialist scope review before a category is selected?
Related preparation guides
- The LLC Pays Its Owner for Work: What Changes in the Preparation File?
- Personal and LLC Transactions Share a Statement: Build a Reviewable Separation Ledger
- Cash Distributions and Loan Repayments Need Different Transaction Labels
Official sources and document versions
Official source versions checked: 2026-11-10
- Form 5472 (Rev. December 2023) — Rev. December 2023
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.