The Extension Was Requested: Define the Remaining Annual-Filing Deliverables
· 5 min read
The answer for this situation
Once an extension request has been made, define the remaining annual-filing deliverables instead of treating the extension itself as the annual return. Start by identifying the selected return and period and the evidence for the request's current status. Then list the information and work still needed for the supported Form 5472/pro forma package, including counterparty and transaction questions that have not been resolved. A handoff checklist should connect those tasks to responsible people and concrete outputs, not merely repeat that more time was requested. It is also important not to wait indefinitely for a standard approval letter where the IRS generally does not send one. The practical objective is to move from an accurately described extension event to a bounded annual-preparation plan without assuming either task guarantees the other.[1, p.1] [2, p.2]
Which facts change the answer?
The special DE package, relevant reporting year and separate-related-party requirements must be considered on their actual facts. A valid extension affects the applicable filing deadline; it does not replace the return or establish that all information in a draft is correct. This article does not decide that a particular extension was properly filed, promise acceptance or extend payment time. Transaction descriptions and any required attachments still need their applicable conditions, including the Part V limitation concerning items not already reported in Part IV. The checklist is an internal preparation tool, not a new government-required attachment.[1, p.1] [2, p.2]
The official requirements, compared
| Question or field | Official instruction | Conditions and limits | Source |
|---|---|---|---|
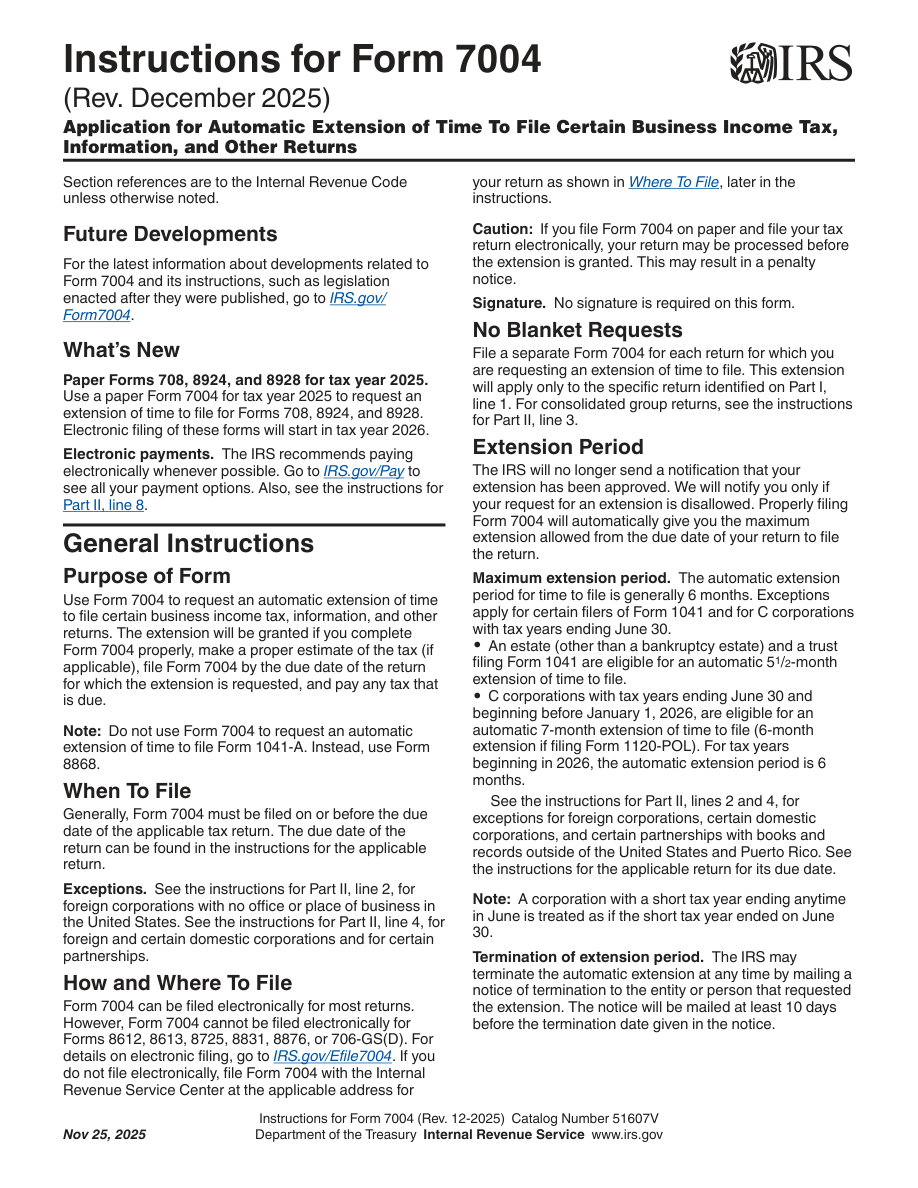
| Separate return | File a separate Form 7004 for each type of return requiring an extension. The extension applies only to the form selected on Part I, line 1. | — | [1, p.1] |
| Disallowance notice only | The IRS generally does not send an extension approval notice and instead notifies the filer if the extension is disallowed. A properly filed application automatically provides the applicable maximum extension period. | — | [1, p.1] |
| De proforma required | A foreign-owned U.S. DE subject to Form 5472 filing attaches Form 5472 to a pro forma Form 1120 and files by the Form 1120 due date, including a valid extension. | — | [2, p.2] |
| Records sufficiency | Keep permanent books and records sufficient to establish the correctness of the federal return and the treatment of related-party transactions, together with the detailed requirements of Regulations section 1.6038A-3. | — | [2, p.3] |
| Separate related party form | Prepare a separate Form 5472 for each foreign or U.S. related party with which the reporting corporation had reportable transactions. Item 1g is the total number of Forms 5472 for that tax year. | — | [2, p.3] |
| Part5 other de transactions | A foreign-owned U.S. DE checks Part V and attaches a description for other specified transactions not reported in Part IV, including receipts and payments connected with formation, dissolution, acquisition, disposition, contributions and distributions. | Foreign-owned U.S. disregarded entity. The relevant transactions have not been reported in Part IV. | [2, p.6] |
Read the requirements in context
De tax year
A foreign-owned U.S. DE uses the tax year its owner uses for U.S. tax filing. If the owner does not have such a tax year, the DE uses a calendar year.[2, p.2]
Original due date
Form 7004 generally must be filed on or before the original due date of the return being extended. Check that return's specific instructions for its original deadline.[1, p.1]
A worked preparation example
This example is hypothetical; it shows how to organize the facts, not an agency decision.
Suppose a hypothetical owner has a Form 7004 copy and believes the annual job is finished. The retained records, however, do not yet identify every relevant related party, and a formation funding description remains incomplete. The preparer creates a handoff checklist with separate entries for the extension record, the reporting-period facts, the party information, transaction support, draft preparation and eventual package submission. The owner is asked to resolve the specific funding description rather than simply upload more files. A related party already appearing in one part of the information is still reviewed for the other applicable identification requirements. When Part V is considered, its stated DE scope and no-duplicate-Part-IV condition remain visible. The extension record stays attached to its selected return and period instead of serving as proof that the annual package exists. If the service message confirms only preparation, the checklist does not silently upgrade that to submission. This hypothetical handoff produces named remaining tasks and clear milestones. It does not establish that the extension was valid or that the eventual return has been filed, accepted or relieved from any unrelated issue.[1, p.1] [2, p.2]
Turn the records into a usable filing plan
For each deliverable, state what the output will be and what evidence will support completion. A resolved factual question, an assembled draft and information supporting actual submission should remain separate milestones. Give unresolved items a specific follow-up owner so the extension does not become a reason to lose track of the preparation work. If a later notice changes the understanding of the request, add it to the relevant record rather than rewriting the entire history as if it had always been known. SpeedEIN's extension preparation and annual preparation should be discussed as their respective supported services, not as an automatic all-in-one result. Neither a request nor an internal checklist completes the later return, extends payment time or guarantees what the government will decide about the actual package.[1, p.1] [2, p.2]
Three checks before you proceed
- Which selected return and period are supported by the extension record, and what is its actual documented status?
- What specific party, transaction or period information is still needed for the eventual annual package?
- Are preparation, submission evidence and any government outcome separate deliverables rather than one assumed completed service?
Related preparation guides
- Changing Preparers After Requesting an Extension: Transfer the Filing Evidence
- The LLC's Extension and the Owner's Return Are Different Filing Jobs
- Keeping Form 7004 Evidence When the IRS Does Not Send an Approval Letter
Official sources and document versions
Official source versions checked: 2026-11-10
- Instructions for Form 7004 (Rev. December 2025) — Rev. December 2025
- Instructions for Form 5472 (Rev. December 2024) — Rev. December 2024
Get help with the relevant SpeedEIN service
SpeedEIN provides preparation and support within the scope described on its service pages. Review the supported entity types, required information and current service scope before ordering. IRS decisions, processing and any applicable filing or payment obligations remain governed by the official rules.